


Hey, it's Eric.
Every week I talk to buyers in McAllen, Mission, Edinburg, Pharr, and Weslaco who tell me the same thing. They can afford the monthly payment. They have a steady job. But they don't have twenty thousand dollars sitting in savings, and they think that means buying a house is years away.
It doesn't. Down payment assistance Texas programs exist specifically for buyers like you, and in my experience they are one of the most underused tools in the Rio Grande Valley. I've watched buyers go from "maybe someday" to holding keys in a few months because a lender showed them a program they didn't know existed.
This post walks you through what down payment assistance actually is, the main Texas programs first time buyers use, and how to get started right here in the Valley.
Why the Down Payment Feels Like the Biggest Hurdle
When you rent in the RGV, you can easily pay $1,200 to $1,600 a month for a decent three bedroom. A mortgage payment on a similar home is often in the same ballpark. The math works. The blocker is almost always the upfront cash, and that number scares people off. But you don't have to save all of it yourself.
How Down Payment Assistance in Texas Actually Works
Down payment assistance, usually called DPA, is money that helps cover your down payment and sometimes your closing costs. It comes from state agencies, local housing authorities, nonprofits, and some cities right here in the Valley. DPA is almost always paired with a first mortgage like an FHA, conventional, VA, or USDA loan, and your lender sets the whole thing up.
Most DPA falls into two buckets.
Grants you don't repay. Some programs give you the money as a grant. It does not have to be paid back. This is the best case scenario, though grant programs usually have income limits and stricter guidelines.
Forgivable or deferred second loans. This is the more common structure. A second lien covers your down payment, forgiven a little each year you stay in the home, or repaid only when you sell, refinance, or pay off the first mortgage. In my experience, the deferred kind surprises buyers in a good way, because there is no second monthly payment while they live there.
The Main Programs Texas Buyers Use
I'm a realtor, not a lender, so talk to a local lender about current income limits. These are the names you'll hear.
TDHCA My First Texas Home. Run by the Texas Department of Housing and Community Affairs, this is the big state program. It pairs a competitive fixed rate mortgage with down payment assistance, often as a grant or a deferred forgivable second loan. First time buyers are the main audience, though "first time" usually means you haven't owned a home in the last three years. I see this one come up a lot for buyers in Edinburg and Weslaco.
Texas Mortgage Credit Certificate (MCC). Also through TDHCA, the MCC is different. Instead of cash upfront, it gives you a federal tax credit every year for part of the mortgage interest you pay, which can raise your take home pay and help you qualify. Some buyers stack the MCC with down payment assistance. Ask your lender about it.
TSAHC programs for Texas heroes. The Texas State Affordable Housing Corporation runs programs aimed at teachers, police officers, firefighters, EMS workers, correctional officers, and veterans. With so many educators and first responders buying homes in the Valley, this one matters here.
Local and regional assistance. Beyond the state level, some cities and counties in the RGV periodically offer their own homebuyer help, and nonprofits like SETH (Southeast Texas Housing Finance Corporation) have historically served Texas buyers with DPA options. Availability changes, which is exactly why a local lender who does these loans every week is worth more than a month of internet research.
What Lenders Look for When You Apply for DPA
Income limits. Most programs cap household income, usually tied to the area median income for Hidalgo County or Cameron County. Limits move when new numbers are published, so a figure you saw last year may not be current. This is the first thing your lender checks.
Homebuyer education. Many DPA programs require a HUD approved homebuyer education course before closing, usually online and a few hours. Do it early. Buyers who wait have delayed closings over this.
Credit score minimums. You don't need perfect credit. In my experience, buyers with scores in the low to mid 600s can often qualify when DPA is paired with an FHA loan. If your score is lower, a few months of cleanup can open the door.
Primary residence. DPA is for the home you will actually live in. No investment properties.
Purchase price limits. Programs set maximum prices, and RGV prices fit comfortably under most of them. A $180,000 to $250,000 home in Mission or Pharr is exactly what these programs were built for.
A Hypothetical Example, RGV Style
Say you are buying a $200,000 home in Mission with an FHA loan. Your down payment would be 3.5 percent, which is $7,000, plus a few thousand in closing costs.
Now imagine a DPA program covers that $7,000 as a deferred second loan with no monthly payment, and you negotiate a seller credit toward closing costs, which is common in our market. Suddenly the cash you need drops from $15,000 or more to something you can save up in months, not years. Every file is different, but this is why I tell buyers to talk to a lender before deciding they can't afford to buy.
Your Next Steps to Get Started
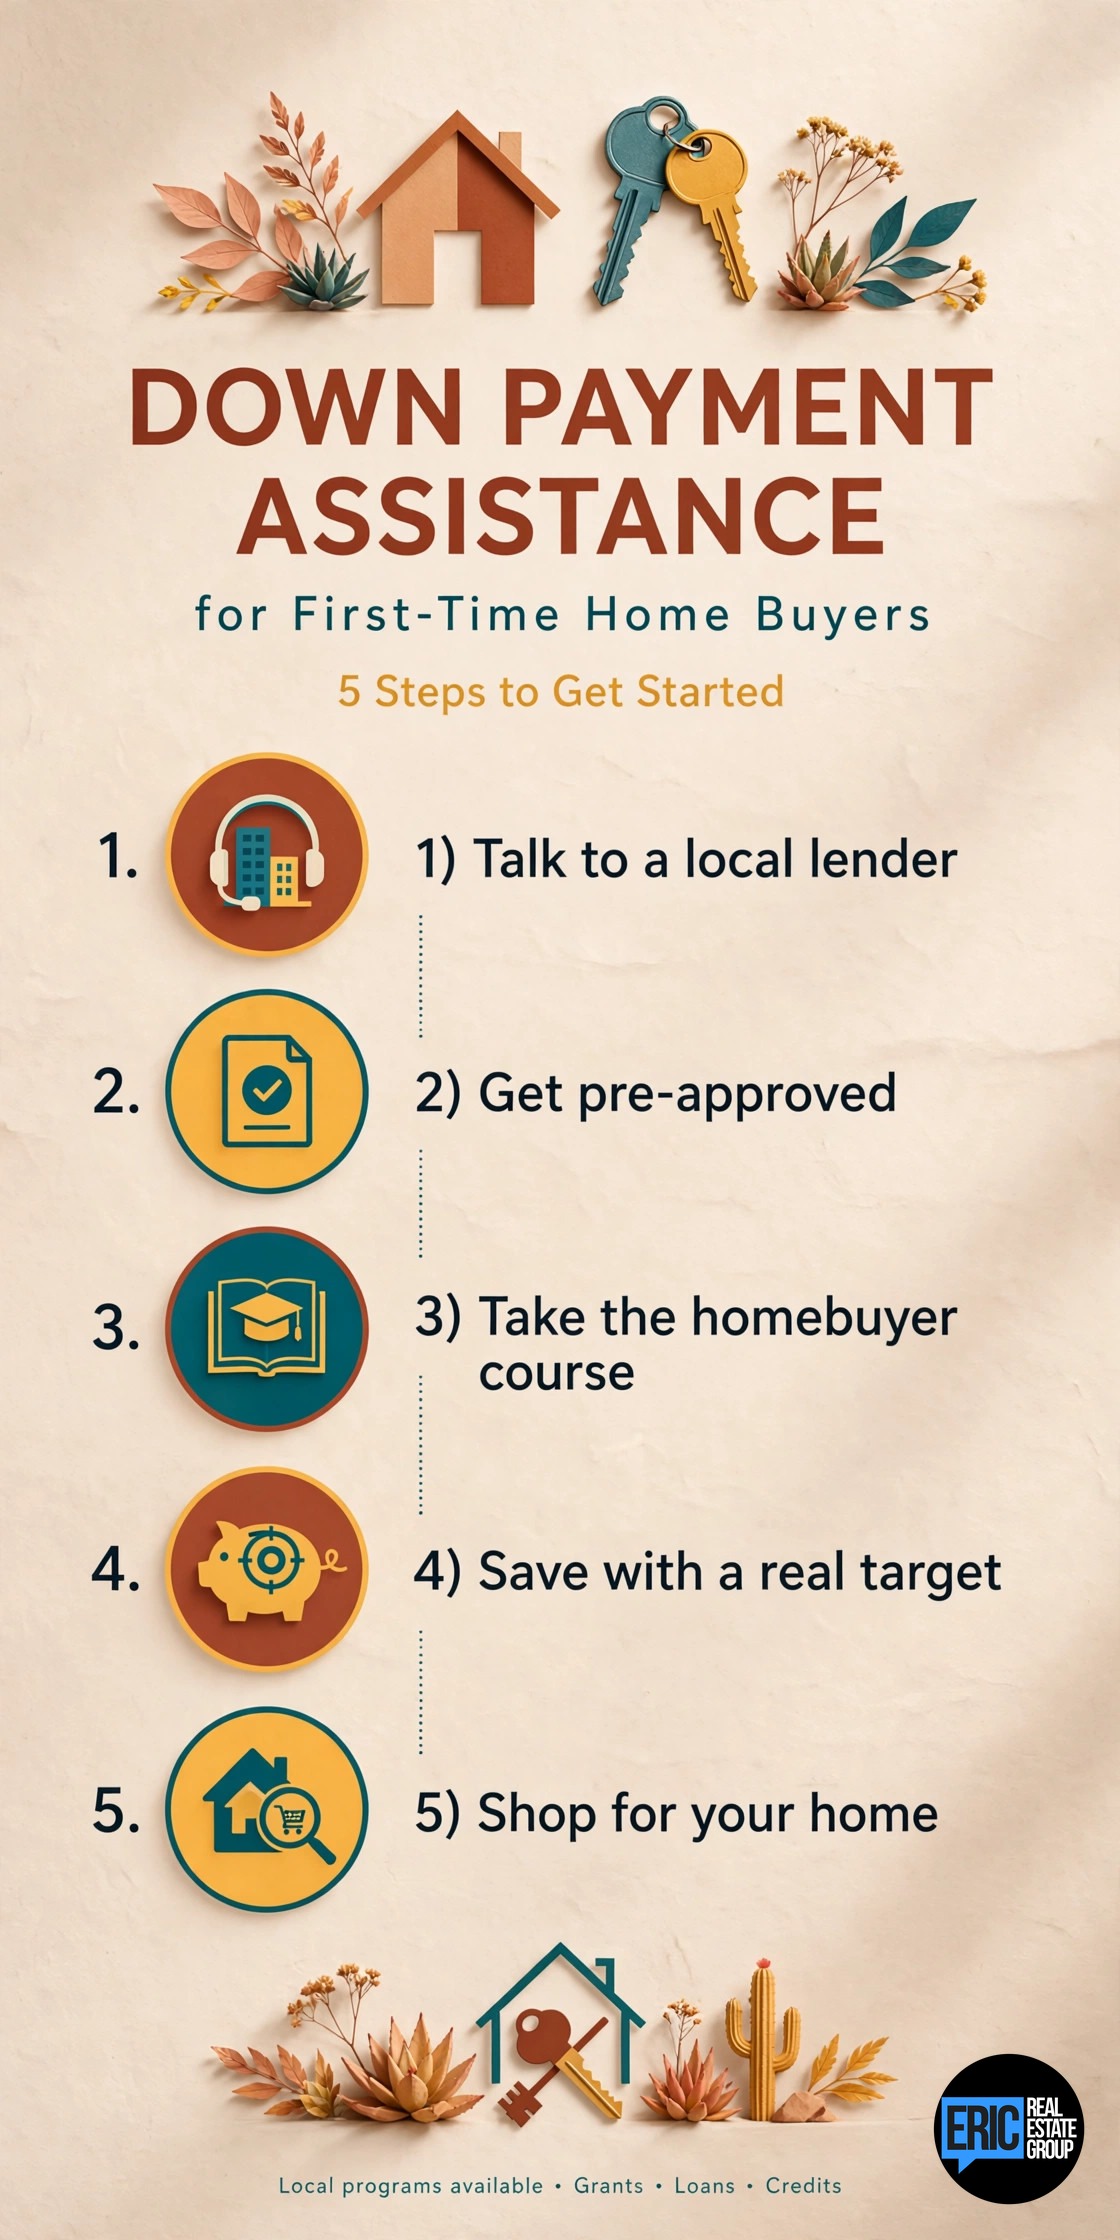
- Talk to a local RGV lender who does DPA loans weekly. Ask, "Do you work with TDHCA and TSAHC down payment assistance?" If they hesitate, find another lender. I work with several who do this every day.
- Get a real pre-approval. Your lender will run your credit, verify your income, check program limits for your household, and tell you exactly which programs you qualify for. This costs you nothing.
- Take the homebuyer education course early. It's a few hours online and it checks a box that cannot wait.
- Keep saving, but with a real target. Once you know your actual out of pocket number, saving becomes a lot less scary. Most of my DPA buyers are surprised at how reachable the number is.
- Call me and let's go look at homes. With a pre-approval that includes your down payment assistance, we can shop confidently. I know which neighborhoods in McAllen, Mission, Pharr, and Edinburg fit DPA price limits, and how to structure offers so your assistance and credits work together.
The Bottom Line
Down payment assistance in Texas is real money for real buyers, and RGV buyers may be the best positioned in the state to use it. Don't let the down payment be the reason you wait another year. Talk to a lender, find out what you qualify for, and let's get you into your own place.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.