


Hey, it's Eric.
I get this question from renters in McAllen all the time. "My rent keeps going up. Should I just buy?" And my honest answer is almost always the same. Let's do the math together, because in the Rio Grande Valley, the numbers tell a story you might not expect.
Buying in McAllen is not just about owning a home. It's about where your money goes every single month and what you have to show for it a few years from now. This post breaks down the real math of renting vs buying in McAllen for 2026, so you can make the call with clear eyes.
The Rent Side: What McAllen Renters Actually Pay
Let's start with what you already know. Rent in McAllen has been climbing. A decent three bedroom home or townhome in a good part of town runs a renter a real monthly number, and that number resets every year when the lease renews. I've had clients tell me their rent went up twice in two years. That's not unusual anymore.
Then there are the hidden costs of renting that never show up on a spreadsheet. The pet deposit. The fee every time you renew. The renter's insurance. The fact that you can't paint a wall, change a fixture, or build a patio without someone else's permission. And the big one. Every dollar of rent is gone. It pays the landlord's mortgage, not yours.
Rent also moves. Owners raise it. Markets shift. The one thing you can count on is that in five years, your rent will almost certainly be higher than it is today.
The Buying Side: A McAllen Mortgage, Piece by Piece
Now let's look at buying. A starter home in McAllen, think three bedrooms in a solid neighborhood, costs a figure that surprises people from out of town. The Valley is one of the most affordable home markets in Texas, and McAllen is right in the middle of that.
Your monthly payment as a homeowner has four main pieces.
Principal and interest. This is the mortgage payment itself. With a fixed rate loan, this part never changes for the life of the loan. Thirty years from now, it's the same number. Think about that next to rent that rises every year.
Property taxes. Texas has no state income tax, so property taxes carry the load. In Hidalgo County they are real money, and buyers should know their neighborhood's tax rate before they shop. But here is the part people miss. The interest and the taxes you pay are costs you would never get back as a renter, yet as a buyer the principal part of your payment is going into your own equity. You're paying yourself.
Homeowner's insurance. Required when you have a mortgage, and in the Valley you want coverage that handles our storms and our weather. It's an annual cost broken into your monthly payment.
Private mortgage insurance (PMI). If you put down less than 20 percent, most conventional loans add PMI. FHA loans have their own mortgage insurance. In my experience, buyers are shocked at how small this is compared to what they expected. It drops off once you build enough equity, so it's temporary, not a life sentence.
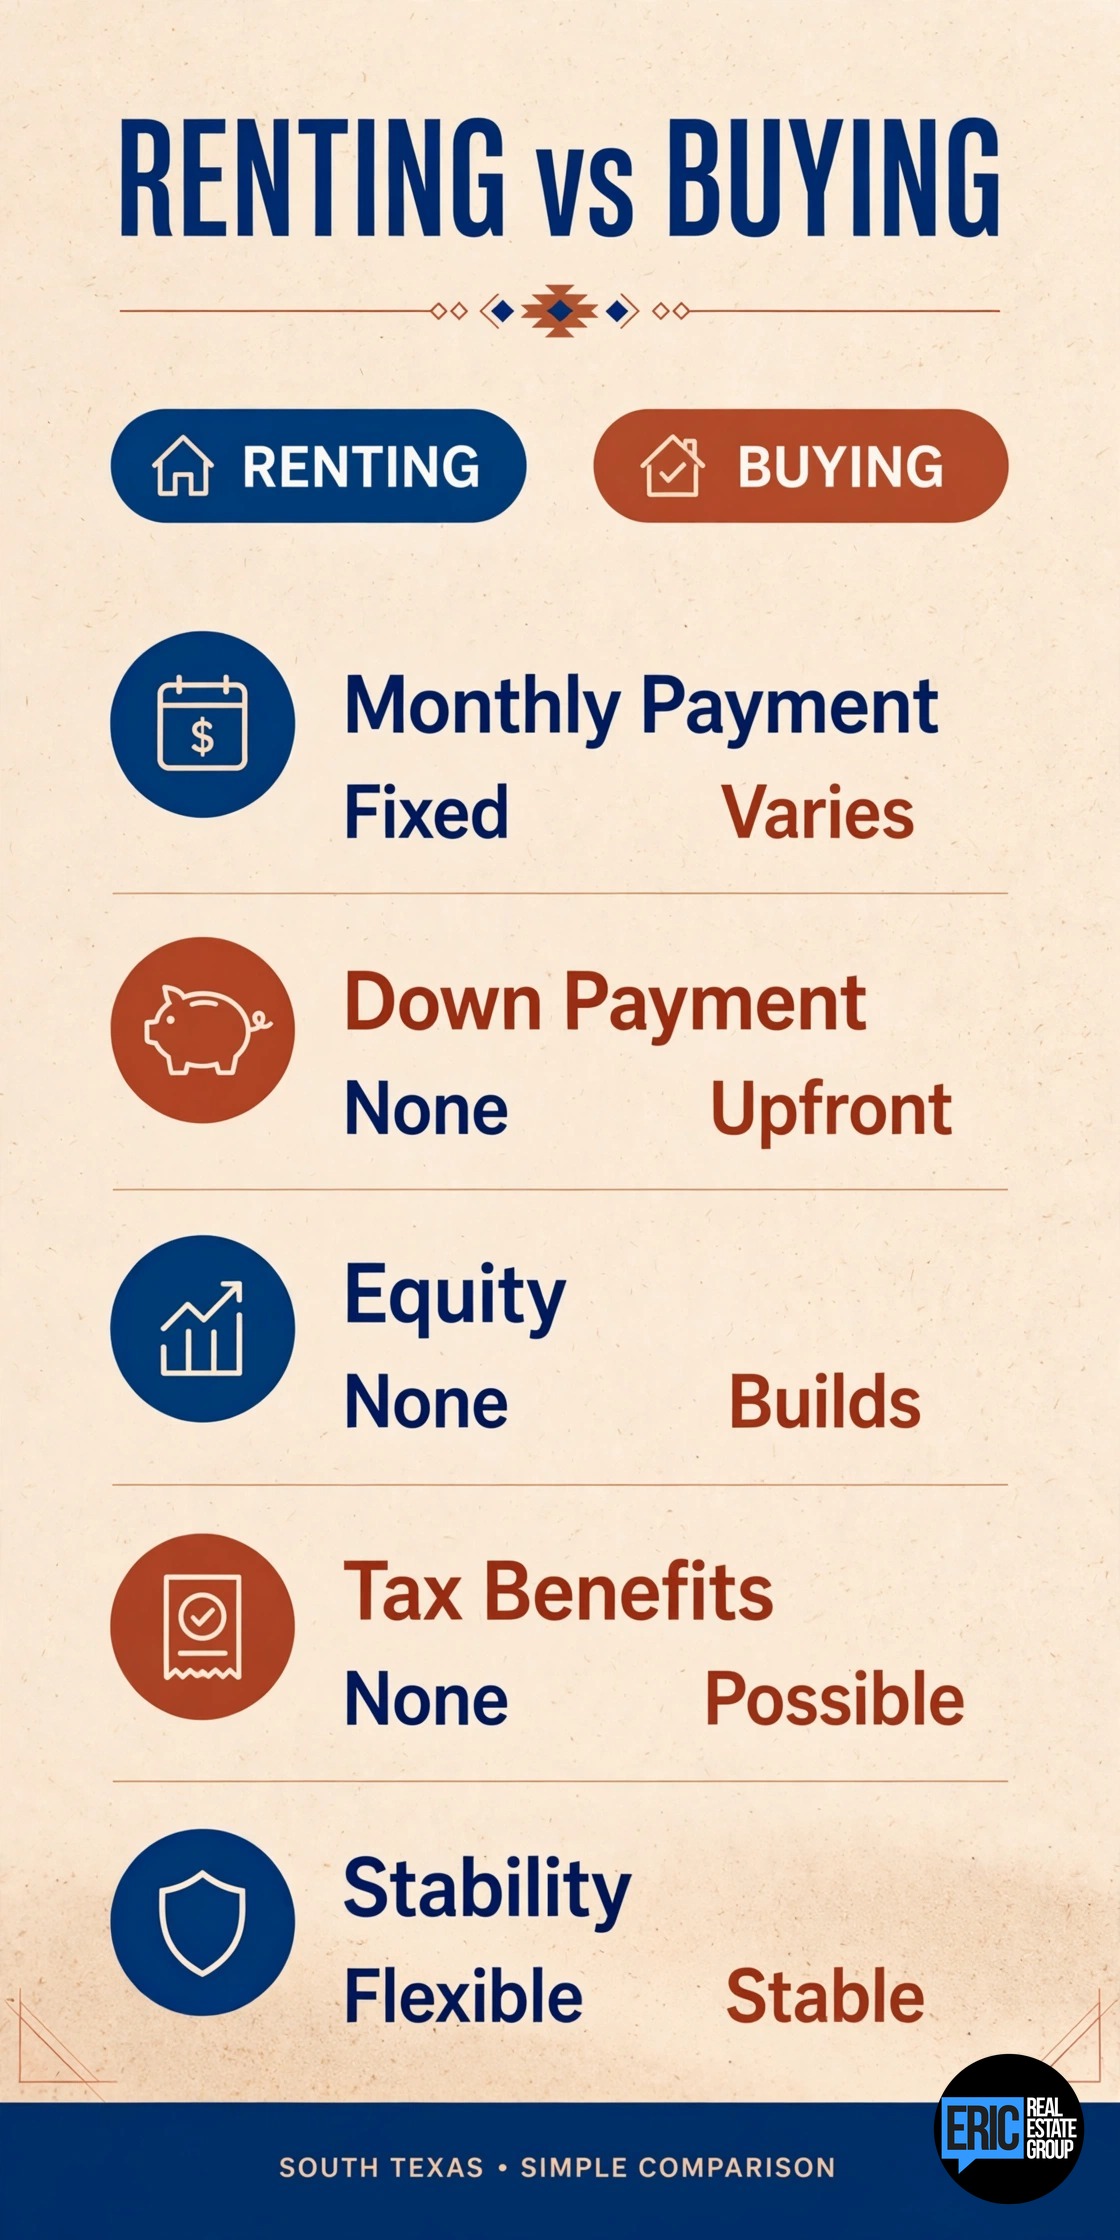
Add those four up, and the monthly cost of owning a comparable McAllen home is often close to what renters already pay each month. That's the part that surprises people. The monthly math is usually competitive. The real difference is what happens to that money.
Where the Money Goes: Rent vs Buy, Year by Year
Here's a hypothetical to make it concrete. Say you're renting a three bedroom in McAllen for around $1,500 a month. That's $18,000 a year, and $90,000 over five years, gone. Not invested. Not saved. Paid to someone else.
Now say you buy a similar home with a low down payment loan. Your monthly payment lands in a similar range. But part of every payment goes toward your loan balance, meaning every month you own a little more of the home. On top of that, if the home holds or grows in value, you're building equity two ways. The part of the payment that reduces your balance is forced savings. Renters don't get that.
This is the real math of renting vs buying in McAllen. It's not just the monthly payment. It's five years from now. The renter has paid a lot of money and owns nothing. The buyer has paid a similar amount and owns equity they can borrow against or roll into their next home.
The Down Payment Question, Answered Honestly
The number one thing that keeps McAllen renters renting is the down payment. Let me be straight with you. You do not need 20 percent down.
FHA loans in Texas let qualified buyers put down as little as 3.5 percent. On a $200,000 home, that's $7,000. Texas down payment assistance programs can cover part or all of that for qualifying buyers, sometimes as a grant you never repay. VA loans offer zero down for eligible veterans, and USDA loans offer zero down in eligible areas outside the city. In my experience, most first time buyers in the Valley bring far less to closing than they feared.
Closing costs add a few thousand more, and there are ways to manage those too, including asking the seller for a credit, which is common in our market. I walk my buyers through every line before they sign anything.
When Renting Still Makes Sense
I'll be honest, because that's what I'd tell you over coffee. Buying isn't right for everyone right now.
You might be moving soon. If there's a real chance you leave the Valley within a year or two, renting gives you flexibility. Buying works best when you plan to stay at least a few years.
Your credit needs work. A lower score can mean a higher rate or a tougher approval. A few months of cleanup can change everything. I'd rather help you fix it first than push you into a bad loan.
Your job is unstable. A mortgage is a commitment. If your income is shaky, waiting is the smart move.
You love your freedom. Some people genuinely prefer to call the landlord when the AC dies. Nothing wrong with that.
But if you're planning to stay in McAllen, you have steady work, and you're already paying rent every month, then the math usually leans toward buying. That's not a sales pitch. That's arithmetic.
What to Do If the Math Tells You to Buy
Here's your move list, simple and in order.
- Talk to a local lender. Not a big national call center. A Valley lender who does FHA, VA, and USDA loans every week. Ask what you'd actually qualify for and what your real monthly payment would look like.
- Get pre-approved. It costs nothing, takes a day or two, and tells you exactly what you can spend. Landlords don't ask for this. Sellers do.
- Be honest about your down payment. Tell the lender what you have saved. Let them show you what assistance programs cover. You might be closer than you think.
- Call me and let's look at homes. I work McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan every day. I'll show you what your rent money buys, and we'll run the numbers on real homes, not hypotheticals.
The Bottom Line
Renting vs buying in McAllen isn't really a close call for most long term renters. The monthly payment is often similar. The difference is that one path builds someone else's wealth and the other builds yours.
If you're writing a rent check every month and staying in the Valley, you owe it to yourself to see the math. It might be the most expensive lesson you never learned, or the smartest move you ever made.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.