


Hey, it's Eric.
You are under contract on a home in McAllen, Edinburg, Mission, Pharr, or Weslaco, and then your lender calls. The appraisal came in low. That call can feel like the deal is falling apart, but in my experience it is often a problem you can work through if you slow down, read the report, and choose your next step on purpose. A low appraisal in Texas does not automatically end a purchase. It does change the math, and the math is what we need to fix.
This post is general information from my experience, not legal or lending advice. Your contract and your lender control how your deal works, so confirm every step with them.
The Appraisal Came in Low: What That Actually Means
An appraiser gives an opinion of value based mainly on comparable sales, meaning recent sales of similar homes nearby, plus the condition and features of the home. Your lender uses that value to size your loan. If the value is below your contract price, the lender will generally base the loan on the lower value, not the price you agreed to.
That difference is called an appraisal gap. As a purely hypothetical example, say you agreed to $250,000 and the appraisal comes in at $235,000. The gap is $15,000. Your loan will be figured from $235,000, so someone has to cover that $15,000, the price has to change, or the deal has to be reworked. That example is not a Valley average. It is just clean math.
I covered the other side in my seller guide on Appraisal Gaps for Sellers: When the Value Comes in Under Contract. Sellers face the same gap from the opposite seat, and both sides do better when they treat the report as information.
Read the Report Before You React
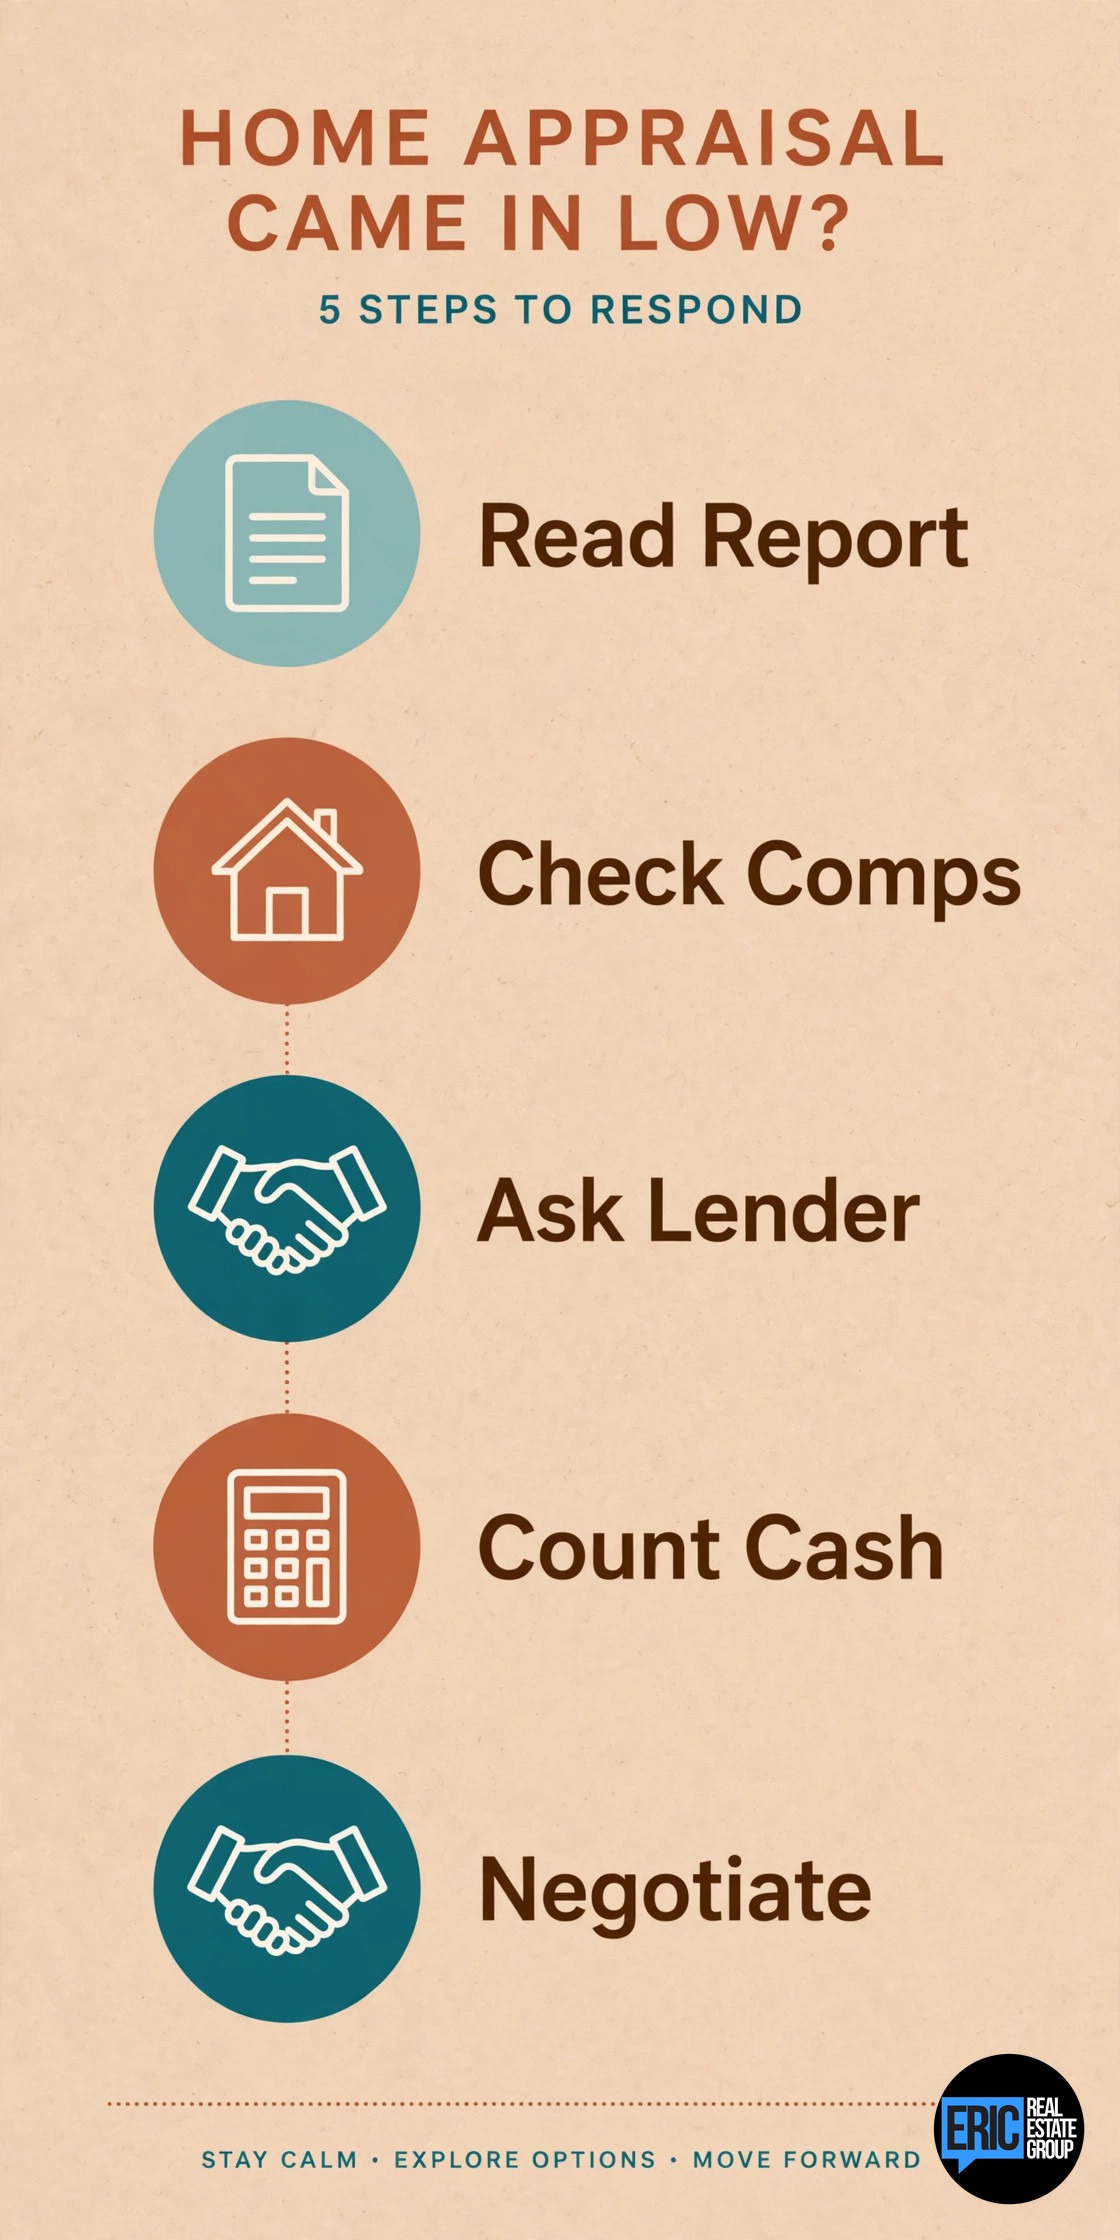
Before anyone renegotiates, read the full report, not just the final number. Look for:
- Which comparable sales the appraiser used, and how recent and how close they are
- Whether the square footage, bedroom and bathroom count, lot size, and condition match the home
- Factual errors, like a missed room or a recent upgrade that was left out
In the Valley this matters. Two homes on the same street in Edinburg or Mission can look alike and be very different inside. A careful read sometimes finds a real error. Sometimes it confirms the value is well supported. Either way, you negotiate better when you know which one you have.
Your Main Options When the Value Comes in Short
Buyers in Texas usually look at some mix of these paths. Your contract terms decide which ones are open to you, so check your deadlines and financing terms before you choose.
- Ask for a reconsideration of value through your lender, with better comparable sales or corrections to factual errors
- Bring extra cash to cover some or all of the gap, if you have it and the home is still worth it to you
- Ask the seller to lower the price to the appraised value, or part of the way there
- Meet in the middle, where the seller drops the price some and you cover the rest
- Use any appraisal or financing rights your contract actually gives you, which can include walking away if the terms allow it and you follow the notice rules exactly
Do not agree to cover a gap verbally. Get any change in writing, in the contract, with your lender aware, before deadlines pass.
Reconsideration of Value: How It Usually Works
A reconsideration of value is not you calling the appraiser and arguing. In my experience, the request goes through your lender, who decides whether to send it forward. A strong request is specific. It points to a factual error, or offers comparable sales that are closer, more recent, or more similar, and explains why in plain language.
A weak request just says the value feels low. That rarely helps. Ask your lender early how long a review could take, because deadlines keep moving while you wait. Work the other options at the same time instead of betting the whole deal on one review.
The Cash Question and Your Loan
Covering a gap with cash sounds simple until you add up everything else due at closing. That cash sits on top of your down payment and closing costs, and it cannot be borrowed from the same loan.
Before you offer to cover any gap, run your full numbers again. I walk through that planning in How Much House Can You Afford in the Rio Grande Valley?, and this is when that check matters most. Ask yourself:
- Will I still have a real emergency reserve left after closing?
- Am I draining money I planned for moving, insurance, taxes, or basic repairs?
If the honest answer is no, a smaller gap share, a price cut, or walking away under your contract rights may be smarter, even when you love the home. Do not close with no cushion left in South Texas, where insurance, taxes, and air conditioning costs are real from month one.
How to Protect Yourself Before You Offer
The best time to plan for a low appraisal is before you write the offer. Talk with your agent and lender about what you would do if value comes in short, and how much cash you could truly bring.
That is part of bidding smart, not just bidding high. I cover that balance in How to Win a Bidding Situation Without Overpaying in the Valley. Buyers who set a clear walk away number before emotions run high handle a low appraisal with less stress. Flag the risk even earlier for neighborhoods with few recent sales, or homes with unusual features like a large workshop or an extra casita, which can be harder to support with comparable sales.
A Simple Checklist When the Appraisal Comes in Low
- Get the full report and confirm the key facts about the home are correct
- Calculate the exact gap in dollars, not just the appraised number
- Ask your lender about a reconsideration of value and how long it could take
- Decide your best mix of price cut request, gap cash, or contract rights, and get it in writing
- Watch every contract deadline while you negotiate, and do not let one pass quietly
The Bottom Line for RGV Buyers
When the appraisal came in low, you still have choices. Read the report, check for errors, ask about a reconsideration with strong comparable sales, recount your cash honestly, and negotiate a written solution that fits the contract and your budget. Some deals close at the appraised value, some split the gap, and some should not close at all. All three can be the right answer.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Search all Rio Grande Valley homes
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.