


Hey, it's Eric.
If you are buying a home in the Rio Grande Valley, you will hear two phrases that sound almost the same but mean very different things to a seller: pre-qualification and pre-approval. Understanding pre-approval vs pre-qualification in Texas can be the difference between getting the house you love in McAllen, Edinburg, Mission, Pharr, Weslaco, or San Juan, and watching it go to another buyer. In my experience, sellers and listing agents trust one of these letters and mostly ignore the other. This guide explains why, and exactly what documents sit behind a real pre-approval.
Pre-Qualification: A Quick Conversation, Not a Verification
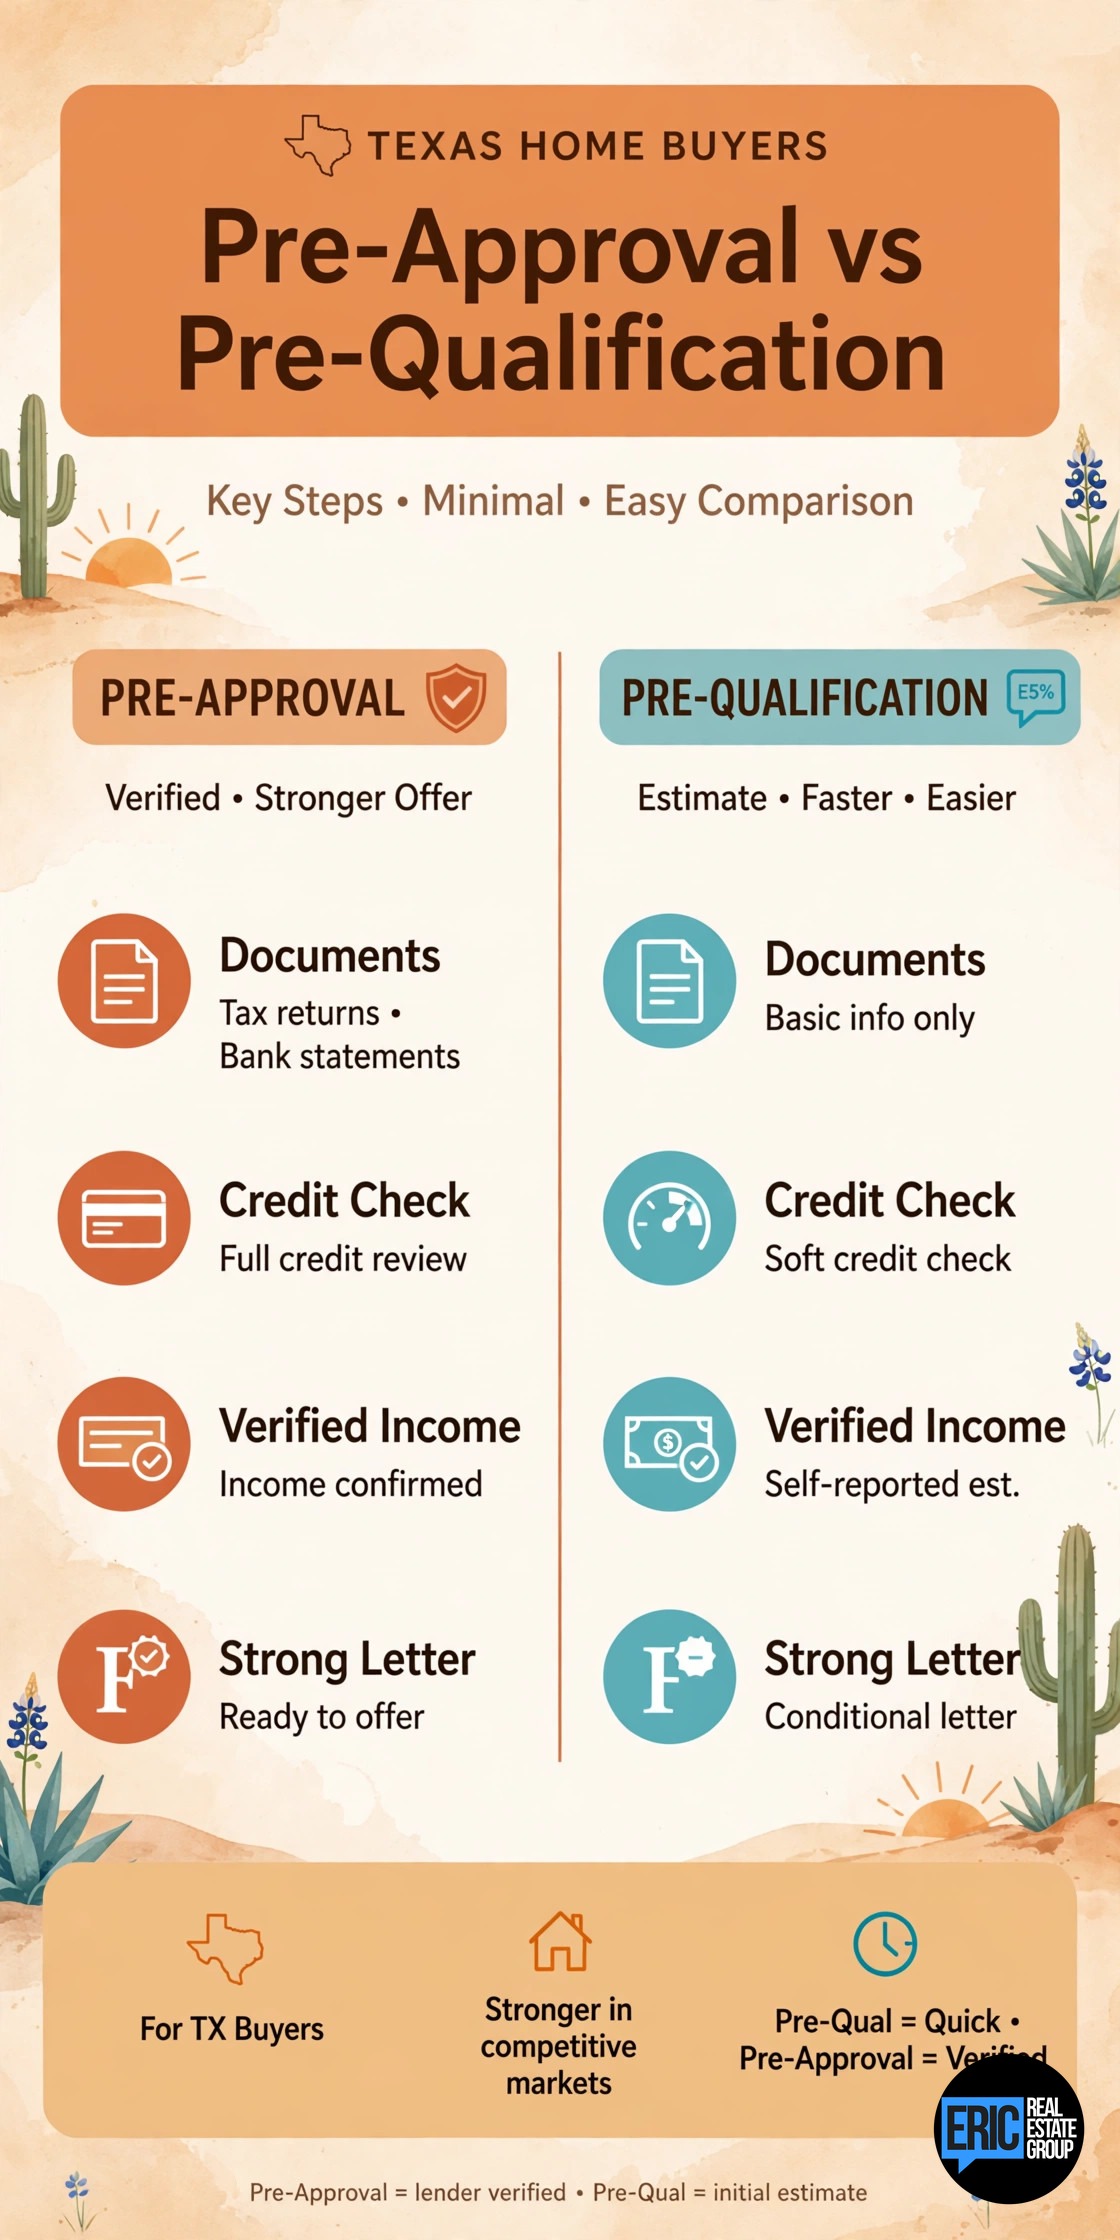
A pre-qualification is usually a short conversation with a lender, sometimes just a form online. You tell the lender your income, your debts, and roughly what you have saved. The lender may or may not pull credit. Nobody verifies your pay stubs, your tax returns, or your bank accounts.
That makes a pre-qualification useful at the very start for a rough price range. It does not make it strong in a contract. It is an estimate based on what you said, not what you proved.
If you are still figuring out your price range, start with my guide on How Much House Can You Afford in the Rio Grande Valley? and then move to a verified letter before you tour homes seriously.
Pre-Approval in Texas: What It Actually Means
A pre-approval means a lender has collected your documents, pulled your credit, and reviewed your income, employment, and assets against a specific loan program. The letter states a loan type and an amount the lender is prepared to lend, subject to the property appraising, title clearing, and your file not changing before closing.
A pre-approval is not a final loan commitment and it is not a guarantee. If you quit your job, buy a truck on credit, or move money around without telling the lender, the approval can fall apart. But compared to a pre-qualification, it is verified work, and sellers know it.
The Document List Behind a Real Pre-Approval
Here is the document list lenders in Texas typically require before they issue a real pre-approval. Exact requests vary by lender and loan type, so use this as your checklist and confirm with your lender.
- Government issued photo ID for each borrower
- Social Security numbers for each borrower, for the credit pull and verification
- Most recent 30 days of pay stubs for each borrower who is employed
- Last 2 years of W2 forms and, if you have other income, the matching records
- Last 2 years of federal tax returns, all pages and schedules, especially if you are self employed, earn commission, or own rentals
- Last 2 months of bank statements, all pages, for every account holding down payment and closing cost funds
- Statements for other assets you plan to use, such as retirement or investment accounts
- Documentation for any gift funds, including the gift letter and paper trail if a family member is helping
- Divorce decree, child support order, or other court orders that affect income or debts, if they apply to you
- Bankruptcy discharge papers and foreclosure dates, if they apply to you
- For VA buyers, your Certificate of Eligibility or DD214 as the lender requests
- Contact information for your employer, so the lender can verify employment
In my experience, buyers who bring this packet complete on day one get their letter faster and cleaner. Buyers who bring it in pieces lose days, and in a competitive week those days cost homes.
I walk through where this step fits in the full sequence in The First Time Buyer's Timeline: From Pre-Approval to Keys in the RGV, from this letter all the way to closing day.
Why Sellers in the RGV Only Trust the Pre-Approval
When I sit with a seller in Pharr or Edinburg and we review offers, we are not just looking at price. We are looking at risk. Will this buyer actually close, and will they close on time?
A pre-approval letter answers that better because:
- A lender has already seen income and assets, not just heard about them
- Credit has been pulled and scored against the loan program
- The loan type is named, such as FHA, VA, conventional, or USDA, so the seller can judge appraisal and condition requirements
- The lender contact is named, so the listing agent can call and verify the file is real and active
A pre-qualification letter answers almost none of that. Listing agents in the Valley call lenders to verify letters every week. When the lender says they have not seen documents yet, that offer drops to the bottom of the stack, even at the same price.
That verification habit is also why strong letters matter so much in multiple offer situations, which I cover in How to Win a Bidding Situation Without Overpaying in the Valley.
A Concrete RGV Seller Scenario Where a Pre-Qual Letter Lost the House
Hypothetical example, based on a pattern I see in my experience. A seller in Mission listed a three bedroom home and received two offers in the first weekend, both at the same asking price.
Offer A came with a pre-qualification letter from an online form. No documents had been verified, no lender phone number was on the letter, and the loan type was not clear.
Offer B came with a full pre-approval. The lender had verified income, assets, and credit, the letter named the loan program and the amount, and when the listing agent called, the lender confirmed the file had been reviewed and only needed a property.
The seller chose Offer B, not because the price was higher, it was not, but because the risk was lower. Offer A might have closed fine. The seller had no way to know that, and sellers are not required to take that gamble. That is the whole lesson in one weekend: at equal price, the verified letter wins.
How to Get Pre-Approved the Right Way in Texas
1. Pick a local lender who closes loans in Hidalgo and Cameron County and who will answer the phone when a listing agent calls.
2. Send the full document list above in one package, all pages, no missing statements.
3. Do not open new credit, buy furniture, or move large deposits without asking the lender first.
4. Ask the lender to match the letter to the exact price range and loan type you will offer in, and to update it for each offer if the amount changes.
5. Give me and the listing agent a lender contact who can verify the letter the same day.
Get the letter before you fall in love with a house in McAllen, Edinburg, Mission, Pharr, Weslaco, or San Juan. Touring first and scrambling for documents later is how good homes get away.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
- Search all Rio Grande Valley homes
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.