


Hey, it's Eric.
If you went through a bankruptcy or a foreclosure, you are not done as a home buyer in Texas. I talk to families in McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan who think they have to wait seven or ten years before they can buy again. That is usually not true. Every major loan program has a defined waiting period, and once that period passes and your credit is reestablished, you can apply again. This guide lays out buying after bankruptcy in Texas loan by loan, so you can plan your timeline with real numbers.
I am not a lender and I am not a bankruptcy attorney. Your lender will verify the current guidelines for your file, and individual lenders can add stricter rules called overlays. Use this as a planning map, then get a lender to run your exact dates.
The Most Important Rule: The Clock Starts at Discharge or Transfer
For bankruptcy, the waiting period usually runs from the discharge date or the dismissal date, not the day you filed. For foreclosure, it usually runs from the date title transferred out of your name, not the day you missed your first payment.
Pull your actual discharge paperwork and, if you lost a home, the date the property transferred. Do not guess from memory. A lender will use those documents, not your estimate. If both events happened, both clocks can apply, and the longer one usually controls, so ask the lender to check both up front.
Waiting Periods After Bankruptcy, Side by Side
Here are the standard agency minimums buyers ask me about most. These are minimums, not guarantees of approval.
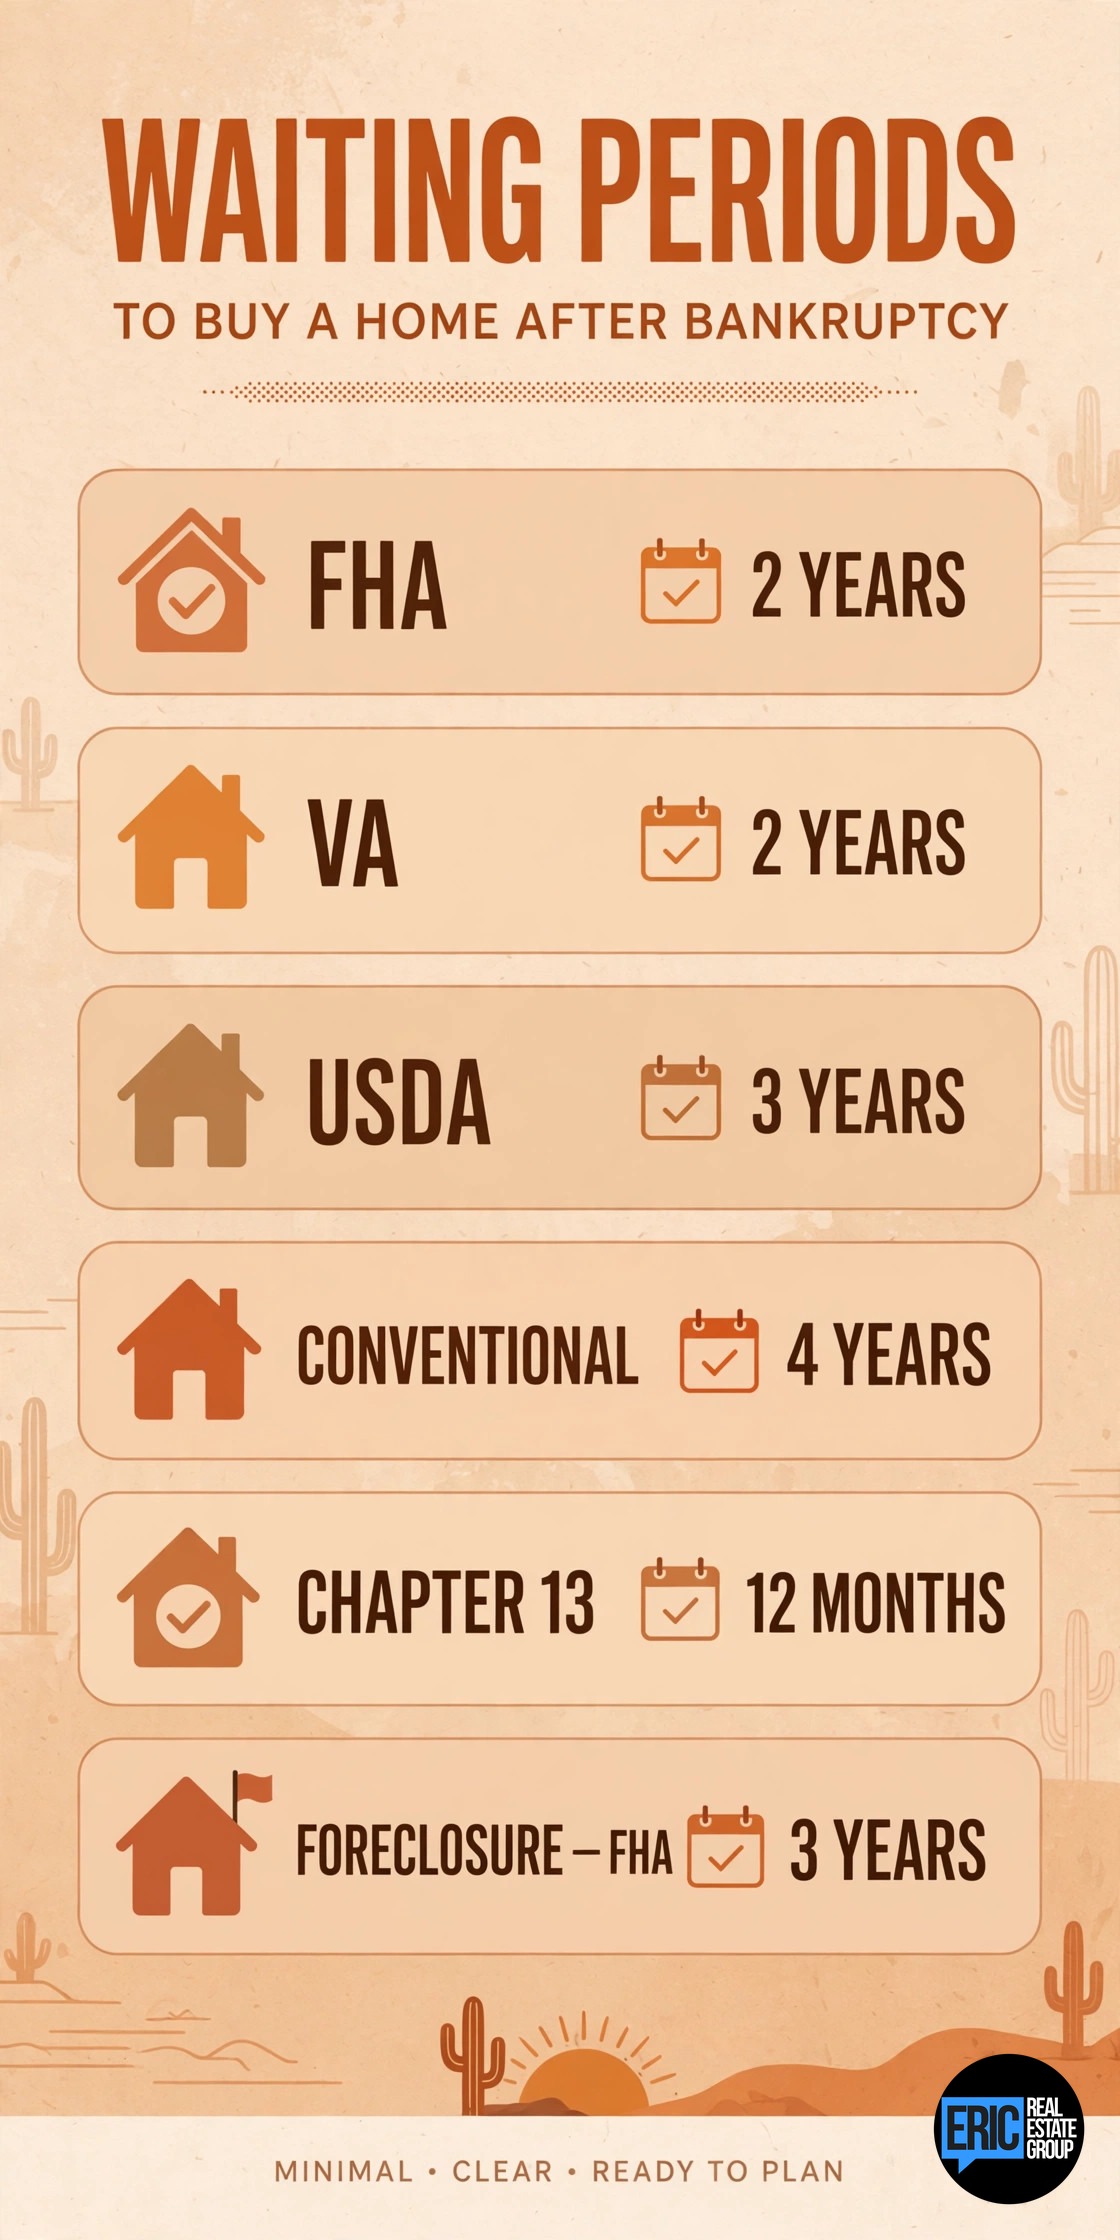
After Chapter 7 bankruptcy, measured from discharge:
- FHA loan: 2 years
- VA loan: 2 years
- USDA loan: 3 years
- Conventional loan: 4 years
After Chapter 13 bankruptcy:
- FHA loan: you may be able to apply after 12 months of on time payments in the repayment plan, with written permission from the bankruptcy court or trustee
- VA loan: you may be able to apply after 12 months of satisfactory plan payments, with trustee or court approval
- USDA loan: you may be able to apply after 12 months of on time plan payments, with trustee approval
- Conventional loan: 2 years from discharge, or 4 years from dismissal
Government backed loans are usually faster after Chapter 7 than conventional loans. Chapter 13 is different because you are repaying creditors under a plan, so FHA, VA, and USDA can sometimes work while the plan is still active.
If you are exploring the government paths, start with my guide on FHA Loans in Texas: Requirements, Limits, and How RGV Buyers Qualify, and ask the lender how your discharge date fits that timeline.
Waiting Periods After Foreclosure, Side by Side
Foreclosure has its own clock, separate from bankruptcy.
Standard waiting periods after a foreclosure:
- FHA loan: 3 years from the date title transferred
- VA loan: 2 years from the date the foreclosure was completed
- USDA loan: 3 years in most lender guidelines
- Conventional loan: 7 years, with a possible shorter period of 3 years when documented extenuating circumstances apply
That seven year conventional wait is why so many Valley buyers who lost a home look first at FHA or, if they are eligible veterans, VA. The home did not end the story. The loan type changes the timeline.
If you are also thinking about buying a bank owned property for your next home, read my notes on How to Buy a Foreclosure or Bank Owned Home in Texas so you understand how those sales work from the buyer side.
What Extenuating Circumstances Can and Cannot Do
Some programs allow a shorter wait when the bankruptcy or foreclosure was caused by a documented event beyond your control, like a serious illness, the death of a wage earner, or a major loss of income that was not likely to repeat. Examples that lenders discuss include FHA possibly going down to 12 months after Chapter 7, and conventional possibly going down to 2 years after Chapter 7, when the circumstances are fully documented.
Lenders want outside documents, a clear timeline, and proof that you have managed credit responsibly since the event. Bring paperwork, not just a story.
Rebuilding Credit While You Wait
The waiting period is only half the job. Lenders also want to see reestablished credit and no new late payments after the event.
In my experience, buyers who come back strongest do these things while they wait:
- Pay every new bill on time, every month
- Keep credit card balances low compared to the limit
- Avoid opening several new accounts at once
- Keep stable employment or steady self employment income
- Save for down payment and reserves in an account the lender can document
- Write a clear explanation letter about what happened and what changed
Your score and your payment history both matter for the rate you get. I explain that connection in How Credit Scores Affect Your Mortgage Rate in Texas, which is worth reading before you apply.
A Hypothetical Valley Example
Hypothetical example only. A buyer in Pharr had a Chapter 7 discharge two and a half years ago and has paid rent and two small accounts on time since then. On the standard minimums above, that buyer has passed the 2 year FHA and VA marks, has not yet reached the 3 year USDA mark, and is still short of the 4 year conventional mark. That does not guarantee approval. It tells the buyer and the lender which programs to price first, and it saves everyone from applying for the wrong loan too early.
Steps to Buy Again in the RGV
1. Pull your discharge or dismissal paperwork and note the exact date.
2. If you had a foreclosure, confirm the exact title transfer date.
3. Check your credit reports for errors and for any new late payments to fix.
4. Talk to a lender who works with buyers after bankruptcy and foreclosure, and ask them to map your dates against FHA, VA, USDA, and conventional side by side.
5. Get a written pre approval for the specific program you qualify under before you tour homes in McAllen, Edinburg, Mission, Pharr, Weslaco, or San Juan.
6. Keep every payment on time through closing and do not take on new debt without asking your lender first.
Sellers in the Valley want certainty. A clean pre approval, documented funds, and a lender who has already reviewed your bankruptcy paperwork make your offer much stronger.
Get your dates, pick the right loan, and rebuild step by step.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
- Search all Rio Grande Valley homes
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.