


Hey, it's Eric.
If you want to learn how to buy a foreclosure or bank owned home in Texas, start with clear eyes. A lower list price can be a real opportunity here in the Rio Grande Valley, but these homes are usually sold as is, with limited disclosures, tighter timelines, and repair costs that land on you after closing. In my experience, foreclosure homes in Texas work best for buyers in McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan who get preapproved first, budget for repairs honestly, and use their option period and inspections to protect themselves.
How to Buy a Foreclosure or Bank Owned Home in Texas: Know the Two Paths
People use the word foreclosure for two different situations.
The first is a home sold at a foreclosure auction. In Texas that process moves fast, usually requires cash or very quick funding, and often gives you little or no chance to inspect inside before you bid. That path carries the most risk.
The second is a bank owned home, also called an REO home. The lender already took the home back and now lists it for sale, often through a listing agent and the MLS. You can usually tour it, make an offer with a contract, and schedule inspections during your option period, just like a regular purchase, but with extra bank forms and stricter deadlines.
For most first time buyers I work with, the bank owned route is the safer place to start. You still need to move with care, but you get more information before your money is fully at risk.
Before you shop either path, read my guide on How Much House Can You Afford in the Rio Grande Valley? A foreclosure budget has to cover the price, closing costs, and repairs, not just the monthly payment.
Get Preapproved and Prove You Can Close
Banks selling these homes want proof you can close. A preapproval letter from a local lender matters, and for auction or investor heavy listings, proof of funds for your down payment and closing costs matters too.
Talk to your lender early about property condition. Some loan programs have minimum rules for the roof, plumbing, electrical, and heating and cooling. If a home has major damage or no working utilities, a standard loan may not work until repairs are made, and the bank seller may not make them. Ask what types of homes your loan can actually buy before you fall in love with a listing. Bring your income and bank documents, and keep a repair budget on top of your down payment.
As a hypothetical example only, a home listed below nearby resale prices can still cost more in the first year if it needs a roof, an air conditioner, and plumbing work all at once. The list price is only the starting point.
Tour Like an Inspector, Then Hire One
Bank owned homes in the Valley have often sat vacant. Vacant homes can hide problems that a quick walk through misses, especially in our heat and humidity.
On your tour, look closely for:
- Water stains, musty smells, or signs of past leaks
- Air conditioning that does not cool, or equipment that is missing
- Cracked windows, damaged doors, and signs of forced entry
- Plumbing fixtures that were removed or damaged
- Roof wear you can see from the ground, and sagging or stained ceilings
- Standing water, drainage problems, or flood signs in the yard and street
Take photos and notes. If you go under contract, hire a licensed inspector during your option period and read the report line by line.
My guide on Home Inspections in Texas: What Buyers Must Check walks through the roof, foundation, electrical, plumbing, and air conditioning checks that matter most here. On a bank owned home that inspection is not a formality. It is how you decide whether to move forward, ask for a price change where the seller allows it, or walk away while you still can.
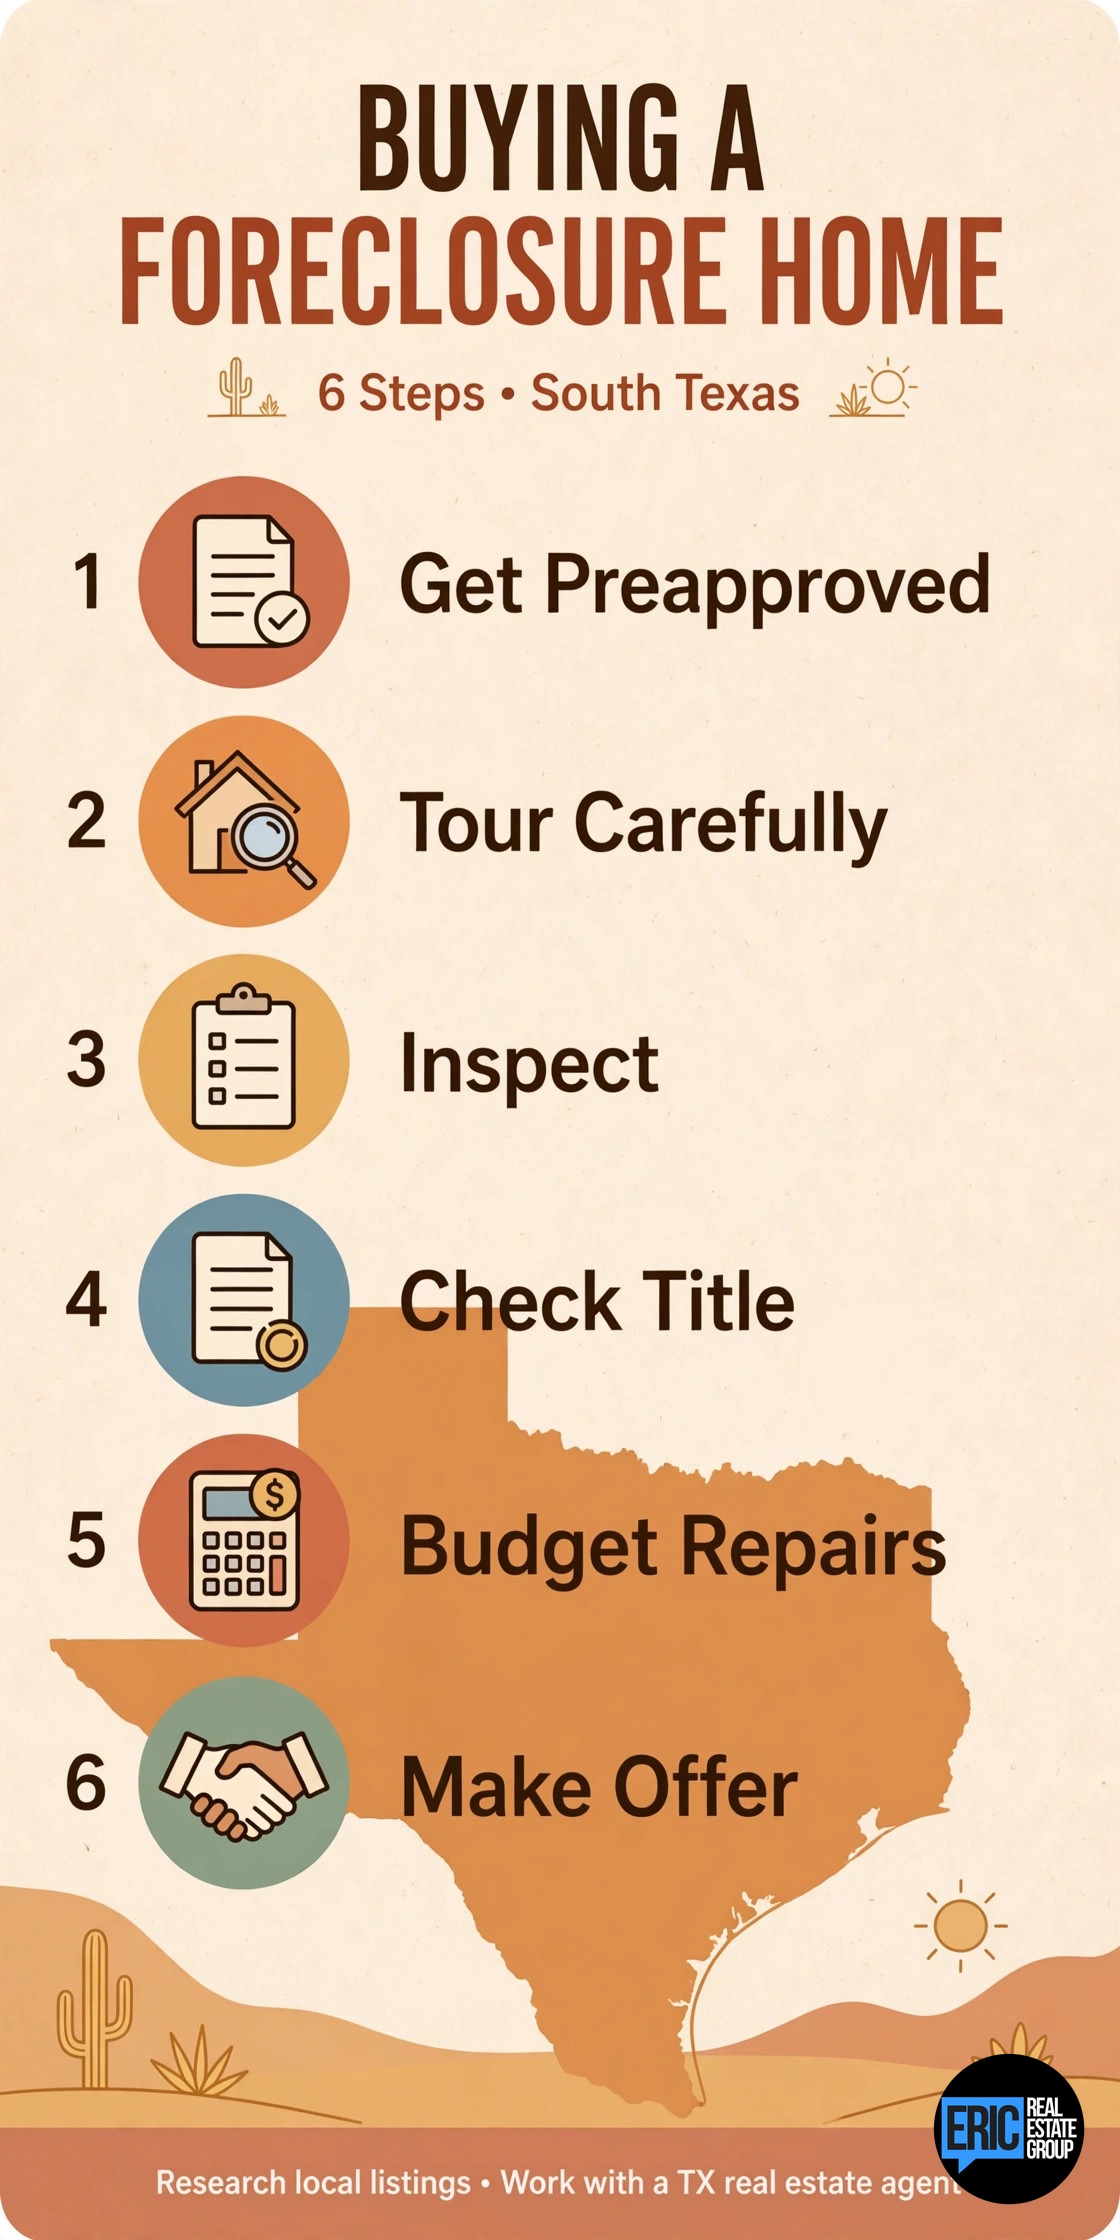
Title, Taxes, and Liens Need Extra Attention
A clean title matters on every purchase, and it matters even more when a home has been through foreclosure. Old liens, unpaid taxes, and paperwork errors can delay or block a sale if they are not cleared.
Work with the title company to review the commitment carefully, confirm property taxes, and ask what exceptions remain. Do not skip owner title insurance because the price looks like a deal.
My guide on Title Insurance in Texas: Why Buyers Need It explains what a policy covers and why buyers in Texas need that protection long after closing day. On a foreclosure purchase, bring your title questions early, not the week of closing.
Also ask whether the seller will provide a survey, whether association fees are owed, whether utilities can be turned on for inspections, and who pays for what under the bank addendum. Read every bank addendum before you sign. Those forms can change deadlines, fees, and your rights if closing runs late.
Making an Offer the Bank Will Take Seriously
Bank sellers review offers on price, but they also review risk. A clean, complete offer often beats a slightly higher offer that looks shaky.
In my experience, a strong bank owned offer usually includes:
- A current preapproval letter and proof of funds
- A realistic closing timeline you and your lender can meet
- Earnest money and option money handled exactly as the contract requires
- Few loose ends, with all forms signed and submitted together
Be ready for a slower reply than a regular seller would give. Keep your option period dates front and center once you are under contract. Missing a deadline can cost you money. Price your offer with repairs in mind, and get contractor quotes during the option period when access allows it, especially for the roof and air conditioning.
After Closing: Budget the First Ninety Days
Plan to change locks right away, set up utilities, and handle safety items first. Service the air conditioner, check smoke detectors, and fix any active leak before cosmetic work. Hold back a repair reserve. Vacant homes can reveal new issues once water and power are back on full time. Tackle safety, roof, and cooling first, then paint and upgrades.
The Bottom Line for Valley Buyers
How to buy a foreclosure or bank owned home in Texas comes down to preparation. Choose the bank owned path if you need inspections and financing, get preapproved for the homes your loan can actually buy, inspect hard, review title early, and budget repairs as part of the price. A good deal is a home you can close on, repair, insure, and live in without draining your savings.
If you see a foreclosure or bank owned listing in McAllen, Edinburg, Mission, Pharr, Weslaco, or anywhere in the Valley and you want a second set of eyes before you offer, call me. We will walk the numbers and the risks together.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Search all Rio Grande Valley homes
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.