


Hey, it's Eric.
If you are buying a home in the Rio Grande Valley, one number will follow you through the whole process. Your credit score. How credit scores affect your mortgage rate in Texas is not just lender talk. It can change your monthly payment, the loan programs you qualify for, and whether a lender says yes at all. Buyers in McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan ask me about this every week, and the good news is that you have more control over it than you think.
In my experience, the buyers who do best are not always the buyers with perfect credit. They are the buyers who checked their credit early, fixed what could be fixed, and gave themselves time before they started touring homes.
How Credit Scores Affect Your Mortgage Rate in Texas
Lenders use your credit score as a quick way to judge risk. A higher score tells a lender you have a track record of paying on time. A lower score tells a lender there is more risk, and lenders usually price that risk into the rate, the fees, or the loan options they offer you.
That does not mean a lower score ends your home search. It means your path may look different. You might qualify for one program and not another. You might need a larger down payment. You might pay more each month for the same house than a buyer with a stronger score would pay. That is why this conversation needs to happen before you fall in love with a house, not after you are under contract.
If you are still working out your budget, start with my guide on How Much House Can You Afford in the Rio Grande Valley? so you see how rate, payment, taxes, and insurance all fit together.
What Lenders Actually Look At Beyond the Score
Your score matters, but it is not the only thing on the page. In my experience, lenders in Texas also look closely at:
- Your payment history, especially any late payments on housing or auto loans
- How much of your available credit you are using right now
- How long you have had credit accounts open
- Recent credit inquiries and any brand new accounts
- Your income, your debts, and your down payment
Two buyers can have a similar score and get different answers because the rest of the file looks different. One buyer might have steady income and low debts. Another might carry balances that push the monthly debt picture too high, even with a decent score. Your lender will walk through the full file, so bring honest information to that first meeting.
Different loan programs treat credit differently too. If you want a plain English look at one common option for Valley buyers, read my post on FHA Loans in Texas: Requirements, Limits, and How RGV Buyers Qualify
Why a Small Rate Difference Changes Your Payment So Much
A mortgage runs for many years, so even a modest difference in rate adds up month after month. As a hypothetical example only, imagine two buyers purchasing a similar home in Edinburg with a similar loan amount. The buyer with the stronger credit profile is offered a lower rate. The buyer with the weaker profile is offered a higher rate. Neither example uses a real rate, because rates change and every file is different. The point is simple. Over time, the higher rate buyer pays more in interest for the same house, and that higher payment can also make it harder to keep cash aside for taxes, insurance, and repairs.
That is why improving your score before you apply can be worth the wait for some buyers. For others, waiting carries its own cost. There is no one answer that fits every family in the Valley. We weigh the trade off together with your lender, using your real numbers, not a guess.
Your rate is only one part of your cash picture. Review my breakdown on What Are Closing Costs in Texas? A Buyer's Line by Line Breakdown so you are not surprised by the other costs at closing.
Practical Steps That Can Help Before You Apply
You cannot change your credit history overnight, and you should be careful with anyone who promises a quick fix for a fee. What you can do is steady, practical work:
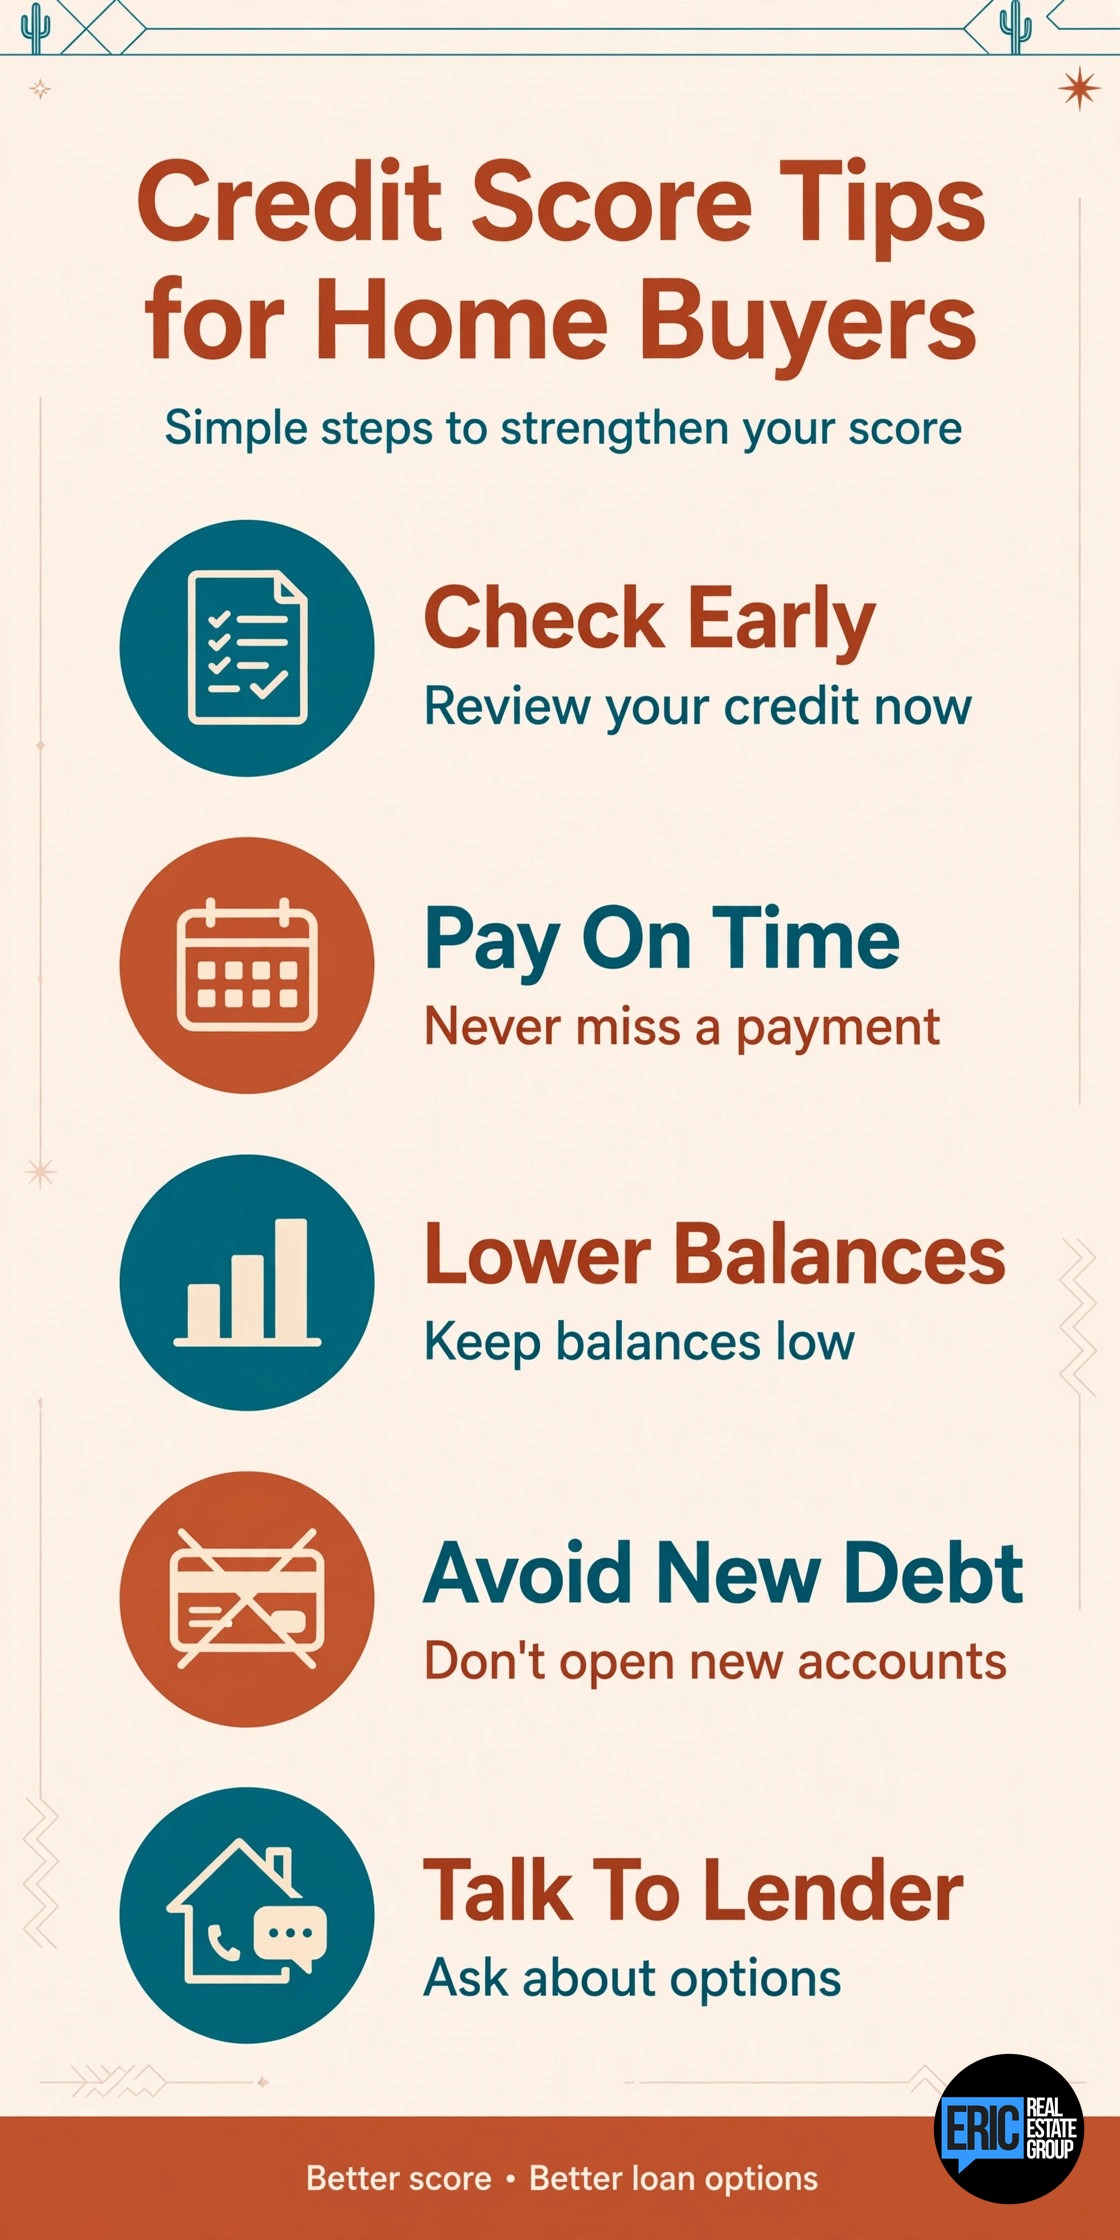
- Pull your credit reports early and check them for errors, accounts that are not yours, and payments marked late by mistake
- Pay every bill on time, every month, especially in the months before you apply
- Avoid opening new credit cards or financing furniture or a car right before you buy
- Keep older accounts open when it makes sense, and talk to your lender before you close any account
- Work on bringing balances down where you can, starting with the accounts your lender flags as the biggest concern
- Keep your paperwork ready, including pay stubs, tax returns, and bank statements, so your lender can see the full picture fast
Do not make a big move with your credit without asking your lender first. Paying off a large balance, closing a card, or moving money between accounts can help in one file and create questions in another. A short call before you act saves a lot of clean up later.
When to Talk to a Lender in the RGV
Talk to a lender sooner than you think you need to. A good local lender will tell you where you stand today, what program fits you today, and what specific steps would improve your options in a few months if you choose to wait. That plan is personal. It depends on your score, your debts, your income, and the kind of home you want in McAllen, Mission, Pharr, or anywhere else in the Valley.
In my experience, buyers who get pre approved early shop with confidence. Sellers take their offers more seriously, and the buyers themselves know their real payment range before they tour. If your score needs work, early is also when you have the most time to do something about it.
Write down the rate discussion, the program discussion, and the next steps from that meeting. Then call me and we will match that plan to real homes that fit your budget.
The Bottom Line for Valley Buyers
Your credit score affects your mortgage rate, your payment, and your loan choices in Texas. It does not define you, and it is not the only factor a lender considers. Check it early, fix errors, pay on time, avoid new debt before you buy, and let a trusted local lender guide any big credit moves.
If you are thinking about buying in the Valley and you are not sure where your credit puts you, call me. We will talk honestly, connect you with a lender who will give you a clear plan, and start your search when you are ready.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Search all Rio Grande Valley homes
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.