


Hey, it's Eric.
If you are self employed in the Rio Grande Valley, you already know the frustration. You make real money running a food truck in McAllen, doing AC work in Edinburg, cutting hair in Mission, hauling, landscaping, selling online, or running a small shop in Pharr or Weslaco. Then a lender looks at your tax return, sees all the deductions your accountant used to lower your taxes, and tells you that on paper you do not qualify. That gap is exactly why bank statement loans and 1099 loans exist, and why so many self employed mortgage Texas buyers ask me about them.
This post explains how buying when you are self employed in the Valley works, what a bank statement loan actually looks at, what a 1099 loan is, and what paperwork to get ready before you start touring homes. I am not a lender, so your lender will verify every program detail for your file. What I can do is help you walk in prepared.
Why Self Employed Buyers Get Stuck With Regular Loans
A regular conventional or government loan usually wants two years of tax returns, and it uses the income left after expenses. If you wrote off mileage, equipment, supplies, and a home office, your taxable income can look much lower than what actually hits your bank account each month.
That does not mean you cannot buy. It means you may need a loan that measures income differently. Some self employed buyers still qualify on tax returns after two stable years, so start by checking the standard path in my guide on FHA Loans in Texas: Requirements, Limits, and How RGV Buyers Qualify.
What Is a Bank Statement Loan?
A bank statement loan is a non qualified mortgage option where the lender uses your bank deposits to estimate income instead of relying only on tax returns. The lender reviews a set number of months of statements, adds up eligible deposits, removes transfers and unusual large deposits that cannot be sourced, and applies an expense factor for your type of work.
Here is the part you must carry into every lender conversation:
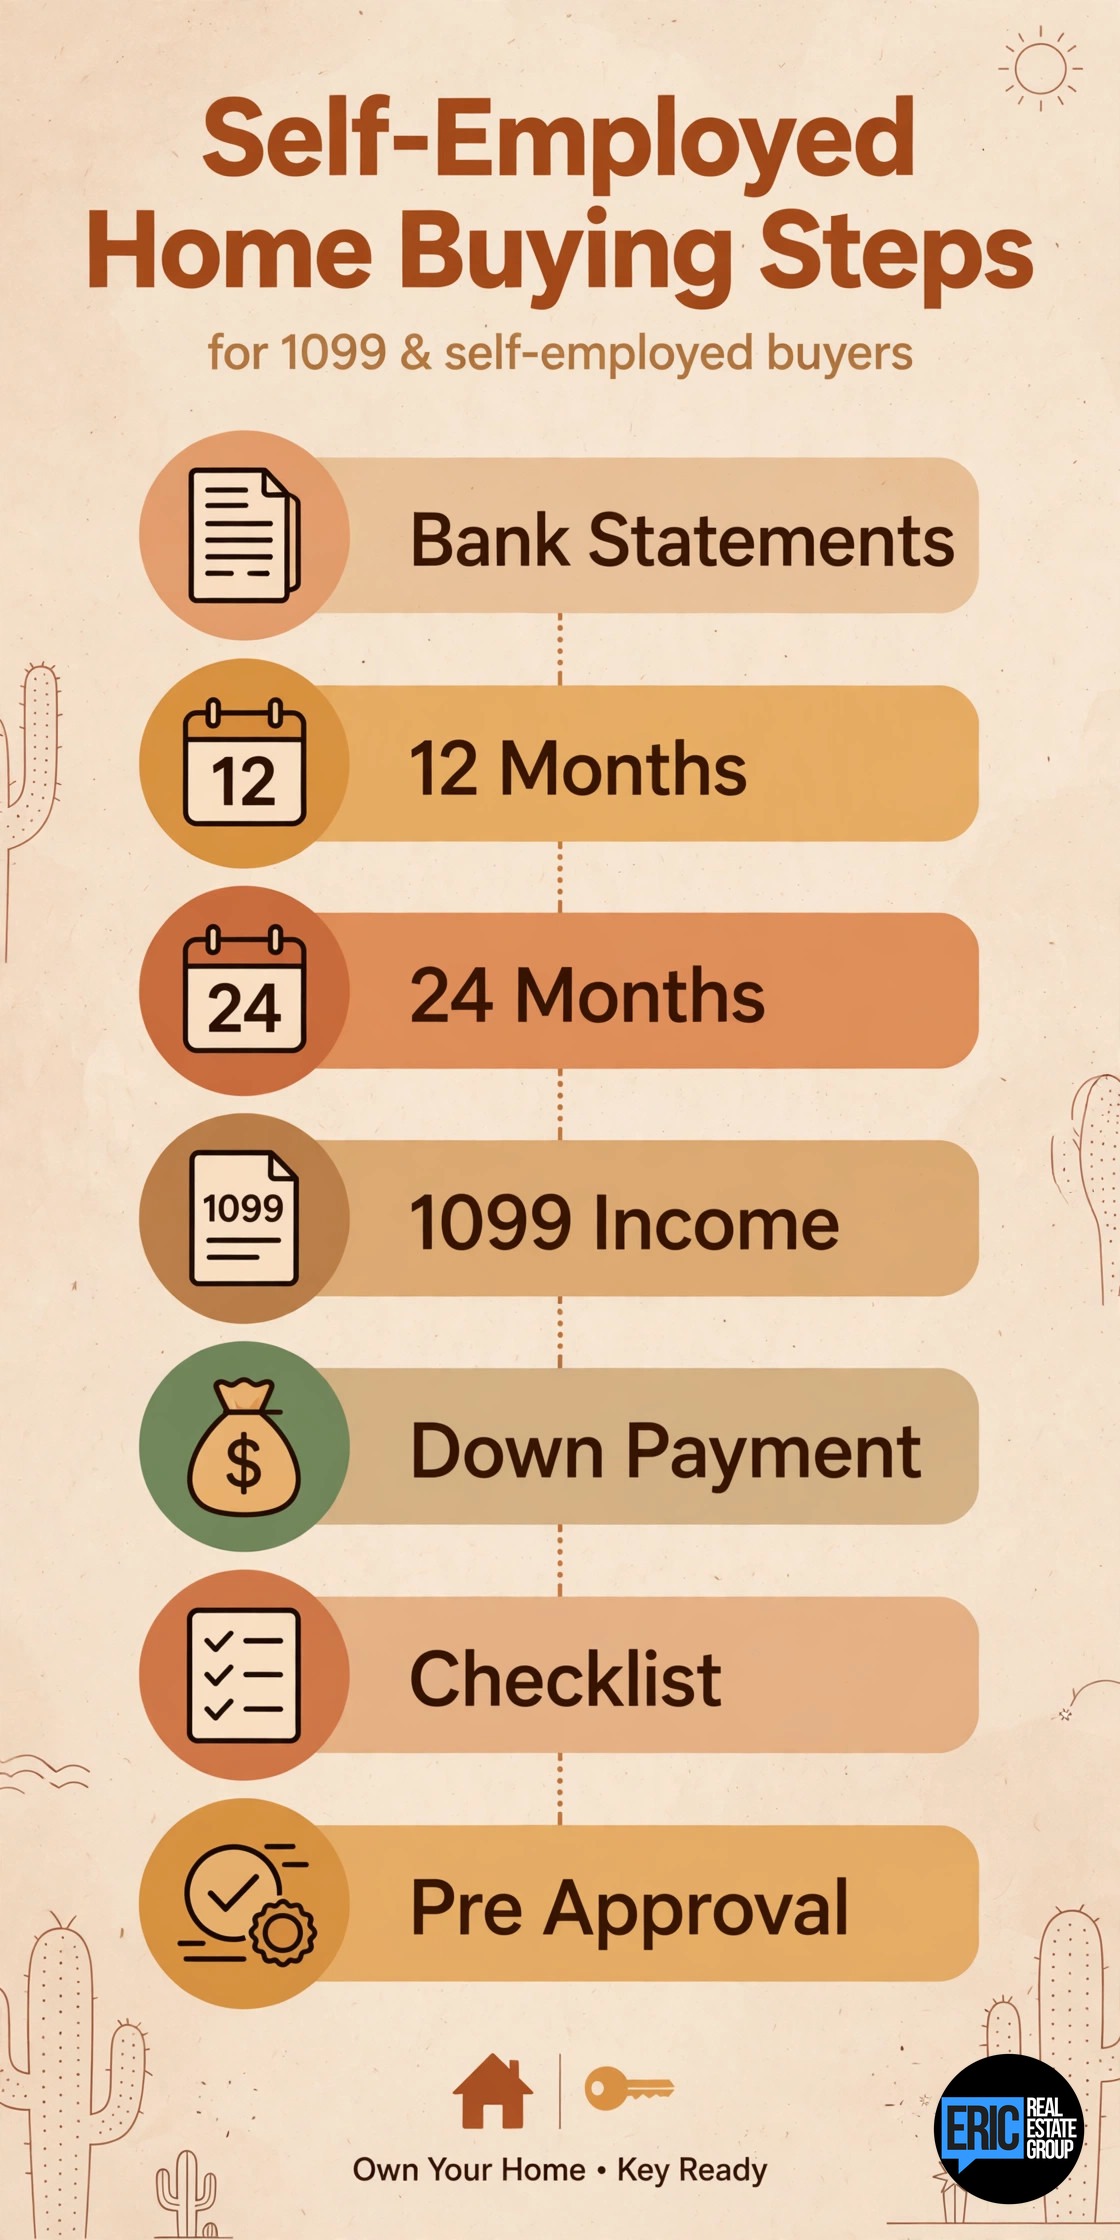
- 12 month bank statement option: the lender reviews 12 months of personal or business bank statements. This can work if your last year was strong and consistent.
- 24 month bank statement option: the lender reviews 24 months of statements. This usually gives a more stable average and can help if one month was slow or seasonal, which is common here with winter visitors, school calendars, and summer heat driving certain trades.
In my experience, lenders like to see the same business, the same accounts, and a steady pattern. Big gaps, new accounts with no history, and mixed personal spending in a business account make underwriting harder.
Before you pick a price range, also review How Much House Can You Afford in the Rio Grande Valley? so your payment target includes taxes and insurance, not just principal and interest.
What Is a 1099 Loan?
A 1099 loan is built for contract workers who get IRS Form 1099 NEC instead of a W 2. Think independent drivers, sales reps, barbers and stylists who rent a chair, real estate and insurance agents, and trades who work as subcontractors around San Juan, Alamo, and the rest of the Valley.
Instead of tax returns alone, the lender uses your 1099 forms, often for one or two years, plus bank statements to confirm the money was deposited. Some programs average the 1099 income over the period reviewed. You will still need to show you are still working in the same line of work at the time of closing.
A 1099 loan is not a no paperwork loan. It is a different paperwork loan.
Typical Down Payment Ranges and Trade Offs
Bank statement and 1099 loans usually require more money down than a low down payment government loan, because the lender is taking on more documentation risk. As a general example range I see lenders discuss, not a quote and not a promise:
- Strong credit and full 24 months of statements: often starting around 10 to 20 percent down in lender examples
- 12 month program, lower credit, or higher loan amount: often 20 to 25 percent down or more in lender examples
- Investment properties or cash out: usually higher down payment or more equity required
Rates and fees on these programs are also usually higher than a standard loan. That is the trade off. You get credit for real cash flow, but you pay for the flexibility. Get the full cost picture in writing, including closing costs, and compare it to waiting and filing taxes differently. My breakdown of What Are Closing Costs in Texas? A Buyer's Line by Line Breakdown can help you read that estimate line by line.
If family is helping with the down payment, ask the lender early how gift funds are treated on that specific program. Rules vary by lender and loan type.
The Documentation Checklist
Get this folder ready before you apply. In my experience, self employed files close faster when nothing is missing on day one:
- Government ID and Social Security information for all borrowers
- Last 12 or 24 months of bank statements, every page, for the accounts you want the lender to use
- Business license, DBA, or proof the business is active, if you have it
- A letter from your CPA, tax preparer, or accountant confirming you are self employed and the business is active, when the lender asks for it
- Year to date profit and loss statement, prepared or signed as the lender requires
- Last one or two years of 1099 NEC forms, for a 1099 loan
- Last two years of business and personal tax returns, even for a bank statement program, because many lenders still review them for activity and consistency
- Proof of any other income you want counted, with deposits to match
- Statements for down payment and reserves, showing where the funds sit and any large deposits explained
- Business bank statements kept separate from personal accounts, if possible, for the cleanest review
Do not move money between accounts without a paper trail during the process, and do not deposit cash you cannot document. Those two habits cause more delays for Valley buyers than almost anything else.
How Lenders Look at Your File in the Valley
Lenders will ask simple questions. How long have you done this work? Is income rising, flat, or falling? Do deposits match the story on your profit and loss? Can you show reserves after closing?
Seasonal work is normal here. AC and roofing pick up in summer, retail and food pick up around holidays and Winter Texan season. A 24 month average can smooth that out. Bring invoices or contracts to explain slow months, and do not open new truck or equipment credit before applying without talking to your lender first.
A Hypothetical Example
Hypothetical example only. A buyer in Edinburg wants a $240,000 home. On tax returns the income looks low after expenses. On 24 months of bank statements, eligible deposits average higher and steadier, so the lender uses that average with its expense factor. With 20 percent down as an example, the loan would be $192,000 before closing costs and prepaids. That does not guarantee approval or a rate. It shows why the documentation method matters, so ask a lender to run both paths and show you the real payment for each.
Steps to Buy When You Are Self Employed
1. Talk to a lender who actually does bank statement and 1099 loans, not just standard loans.
2. Bring the full checklist above to the first meeting.
3. Get a written pre approval that states which program you are approved under.
4. Tour homes in McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan that fit the payment, not just the price.
5. Keep deposits clean and documented through closing, and keep working the same business.
Sellers in the Valley care about certainty. A strong pre approval, a solid down payment, and a lender who answers the phone can make your offer stand out, even when you are self employed.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
- Search all Rio Grande Valley homes
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.