


Hey, it's Eric.
If family wants to help you buy a home in the Rio Grande Valley, gift funds for a down payment can make a real difference. I see this a lot in McAllen, Edinburg, Mission, Pharr, Weslaco, and San Juan. Parents offer to help, the buyer gets excited, and then the lender asks for a paper trail nobody expected. The gift itself is usually not the problem. The problem is a missing letter, a cash deposit with no proof, or money that moved before anyone called the lender.
This guide is general information from my experience, not loan advice for your exact file. Get your lender's gift form before any money moves.
How Gift Funds for a Down Payment Actually Work
A gift is money you do not have to pay back. If you have to repay your parents every month, your lender may treat that money as a debt, not a gift, and that can change your approval.
If you are still comparing loan options, my guide on FHA Loans in Texas: Requirements, Limits, and How RGV Buyers Qualify is a good starting point, and my guide on Down Payment Assistance Programs in Texas: What First Time Buyers in the RGV Should Know covers help that comes from programs instead of family.
In my experience, lenders usually want to confirm four things about a gift:
- Who gave the money, and what is their relationship to you
- That the donor had the money and could give it
- That the exact amount moved from the donor to you, or to the title company
- That no repayment is expected or required
Who counts as an allowed donor depends on your loan program and lender. Do not assume a gift from a friend or employer will be accepted like a gift from close family. Ask your lender in writing first.
The Exact Gift Letter Elements Lenders Require
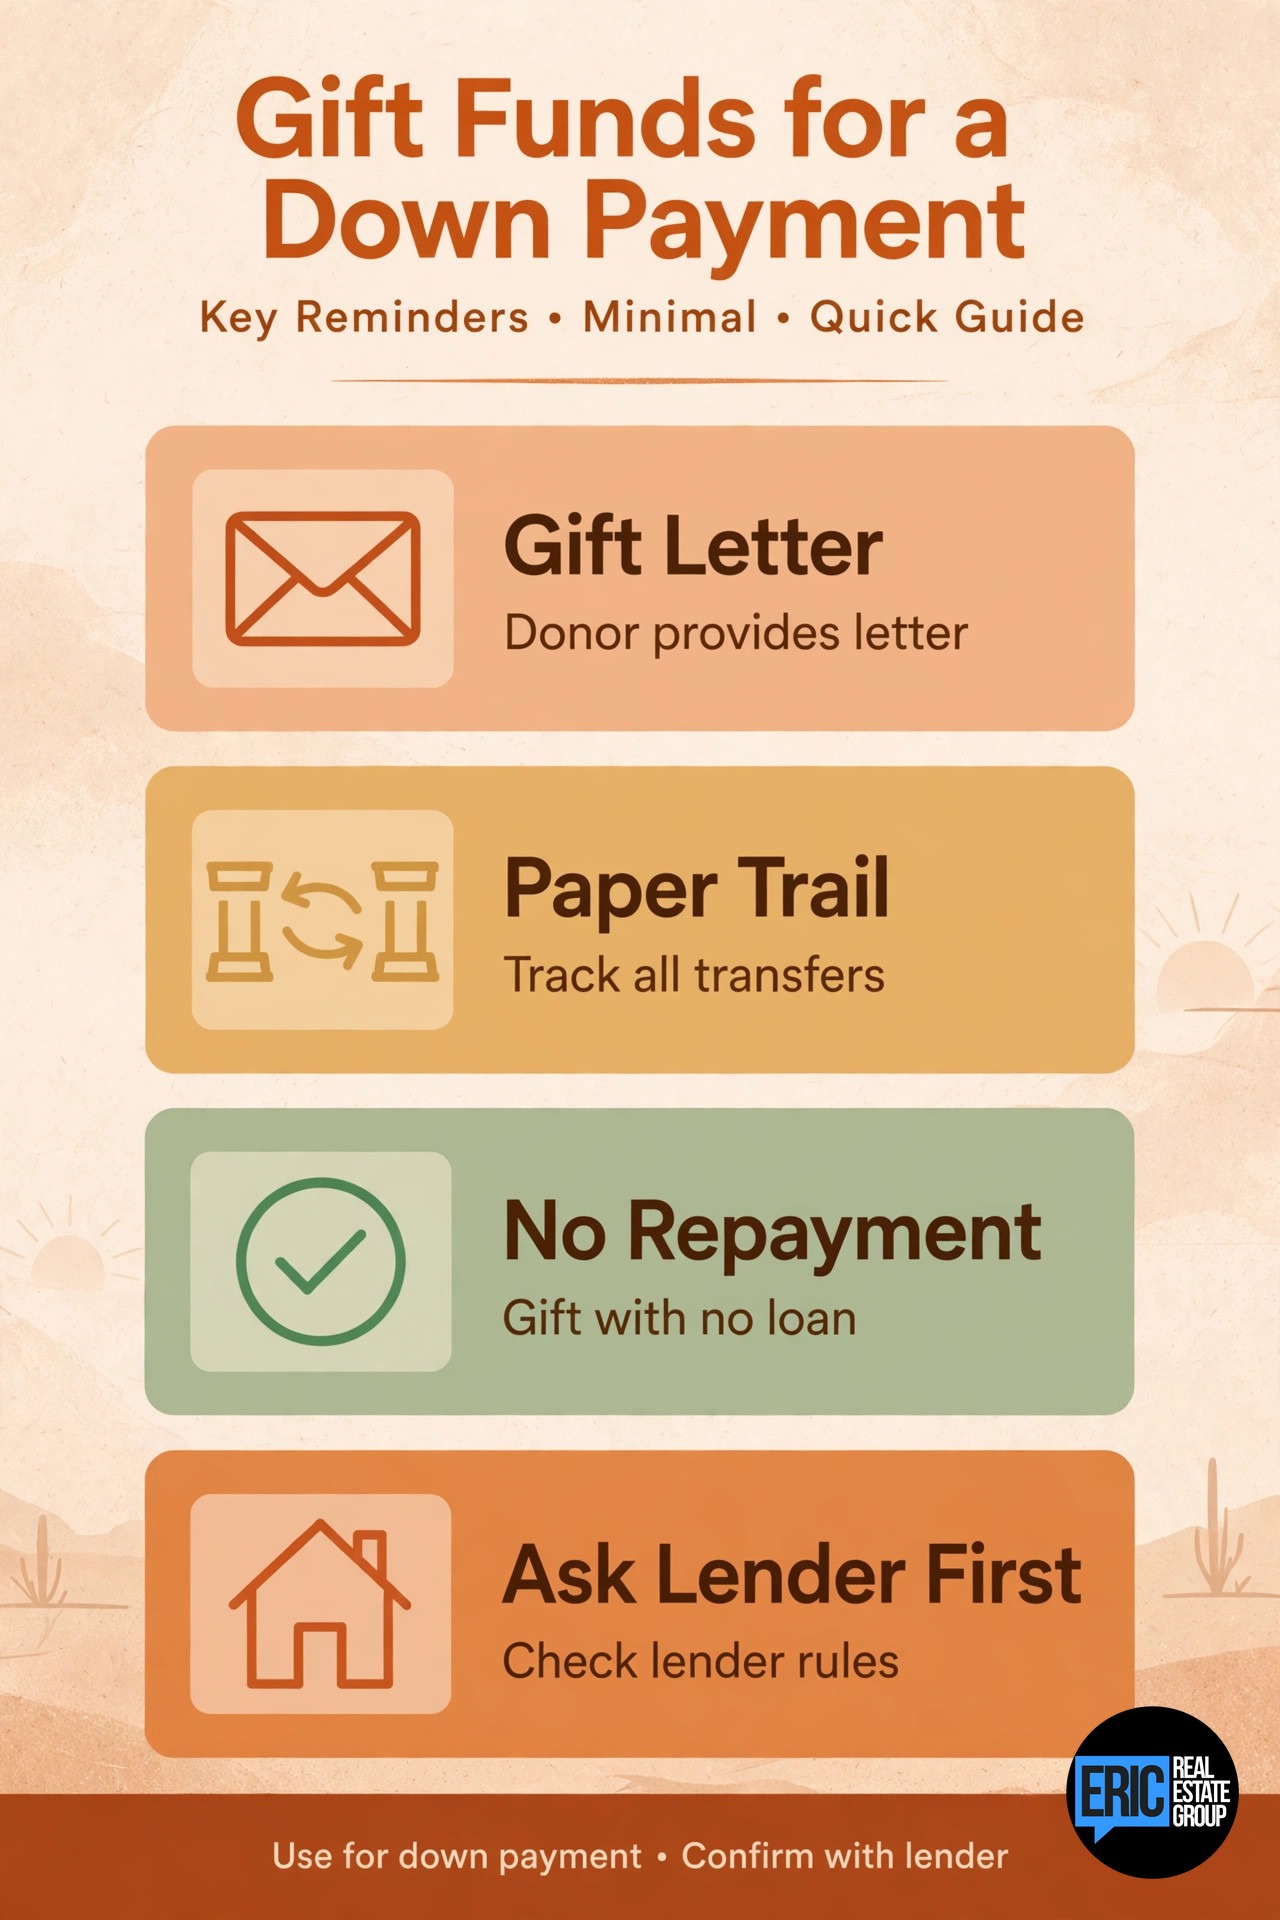
Most lenders have their own gift letter form. Use their form when they give you one. In my experience, a complete gift letter includes all of these elements:
- The donor's full legal name
- The donor's current address
- The donor's phone number
- The borrower's full legal name
- The relationship between the donor and the borrower, for example parent, grandparent, or spouse
- The property address for the home being purchased, when it is known
- The exact gift amount, matching the amount that was actually transferred, to the dollar
- The date of the gift, or the planned transfer date
- A clear statement that the money is a gift
- A clear statement that no repayment is expected or required, in whole or in part
- A statement about the source of the funds, such as the donor's bank or account, when the lender asks for it
- The donor's signature and the date signed
- The borrower's signature and the date signed, when the lender's form asks for it
The amount on the letter, the amount on the transfer proof, and the amount that lands in your account should all match. If the letter says $10,000 and only $9,500 moved, your underwriter will ask questions. Fix the paperwork before closing week, not during it.
The Paper Trail That Proves the Gift
A signed letter by itself is often not enough. Lenders also want documents that show the money moving. In my experience, keep copies of everything below from the start:
- A copy of the cashier's check, personal check, or wire confirmation used for the transfer
- Proof the donor had the funds, such as a donor bank statement page showing the balance before the transfer, with only the information the lender asks for
- Proof the funds left the donor's account
- Proof the same funds arrived in your account, such as your updated bank statement or a deposit receipt
- A short written explanation for any large deposit that is not your regular paycheck
Do not deposit cash you cannot document. Cash is very hard for a lender to source. A check or a wire with records is much cleaner. Do not move the money between accounts unless your lender tells you to, and tell your lender during pre approval, not after you are under contract.
A Sample Dollar Scenario: A $10,000 Gift on a $220,000 Purchase
Here is a hypothetical example only, to show how the numbers can fit together. Your loan terms will be different, and your lender will run your real numbers.
- Purchase price: $220,000
- Hypothetical down payment example: $7,700, which is 3.5 percent of $220,000
- Gift from a parent: $10,000
- Gift applied to the down payment: $7,700
- Remaining gift amount in this example: $2,300, which the buyer could use toward closing costs if the loan program and lender allow it for that file
You still need to plan for closing costs, prepaid taxes and insurance, and reserves after closing. My breakdown of What Are Closing Costs in Texas? A Buyer's Line by Line Breakdown shows those other line items. And if that $10,000 had arrived as cash with no record and no letter, it might sit in your account and still not be usable until it can be fully documented. That is why the paper trail matters as much as the amount.
Limits, Rules, and Mistakes to Avoid
There is no simple Texas rule that caps a family gift at a certain amount for every buyer. The limit that matters is your loan program's rules and your lender's documentation requirements. A larger gift usually means more documentation, not an automatic no.
A few mistakes I want you to avoid:
- Do not call money a gift if there is a side agreement to pay it back
- Do not transfer the money before you ask your lender how they want it sent
- Do not round the amount on the letter or change it after the transfer
- Do not mix gift money with undocumented cash deposits in the same account if you can avoid it
- Do not wait until the week of closing to tell your lender, your title company, or me
Gift tax questions are for the donor and their tax professional. I am not a tax advisor, and this post is not tax advice.
My Bottom Line for Valley Buyers
Gift funds for a down payment can help a first time buyer in the Valley get into a home sooner. The buyers who close smoothly call the lender first, use the lender's gift letter form, transfer money in a way that leaves records, and keep every receipt in one folder. If family help is part of your plan, tell me on our first call and we will build your search around your real payment, your gift, and your closing costs.
Looking to buy or sell in the Rio Grande Valley?
Eric Jimenez | Eric Real Estate Group, LLC | 956-292-4500 | eric@bettercalleric.com | bettercalleric.com
Better Call Eric. Listings that sell.
Start Your Search: Rio Grande Valley Homes for Sale
Reading about the market is smart. Looking at real homes is better. Try one of these searches, then create a free account to save your favorites and get new listings emailed to you the moment they hit the market.
- Homes for sale in McAllen
- Homes for sale in Edinburg
- Homes for sale in Mission
- Search all Rio Grande Valley homes
See a home you like? Call Eric Jimenez at 956-292-4500 and I will set up a showing.